Appendix 4E & Annual Report
View original announcement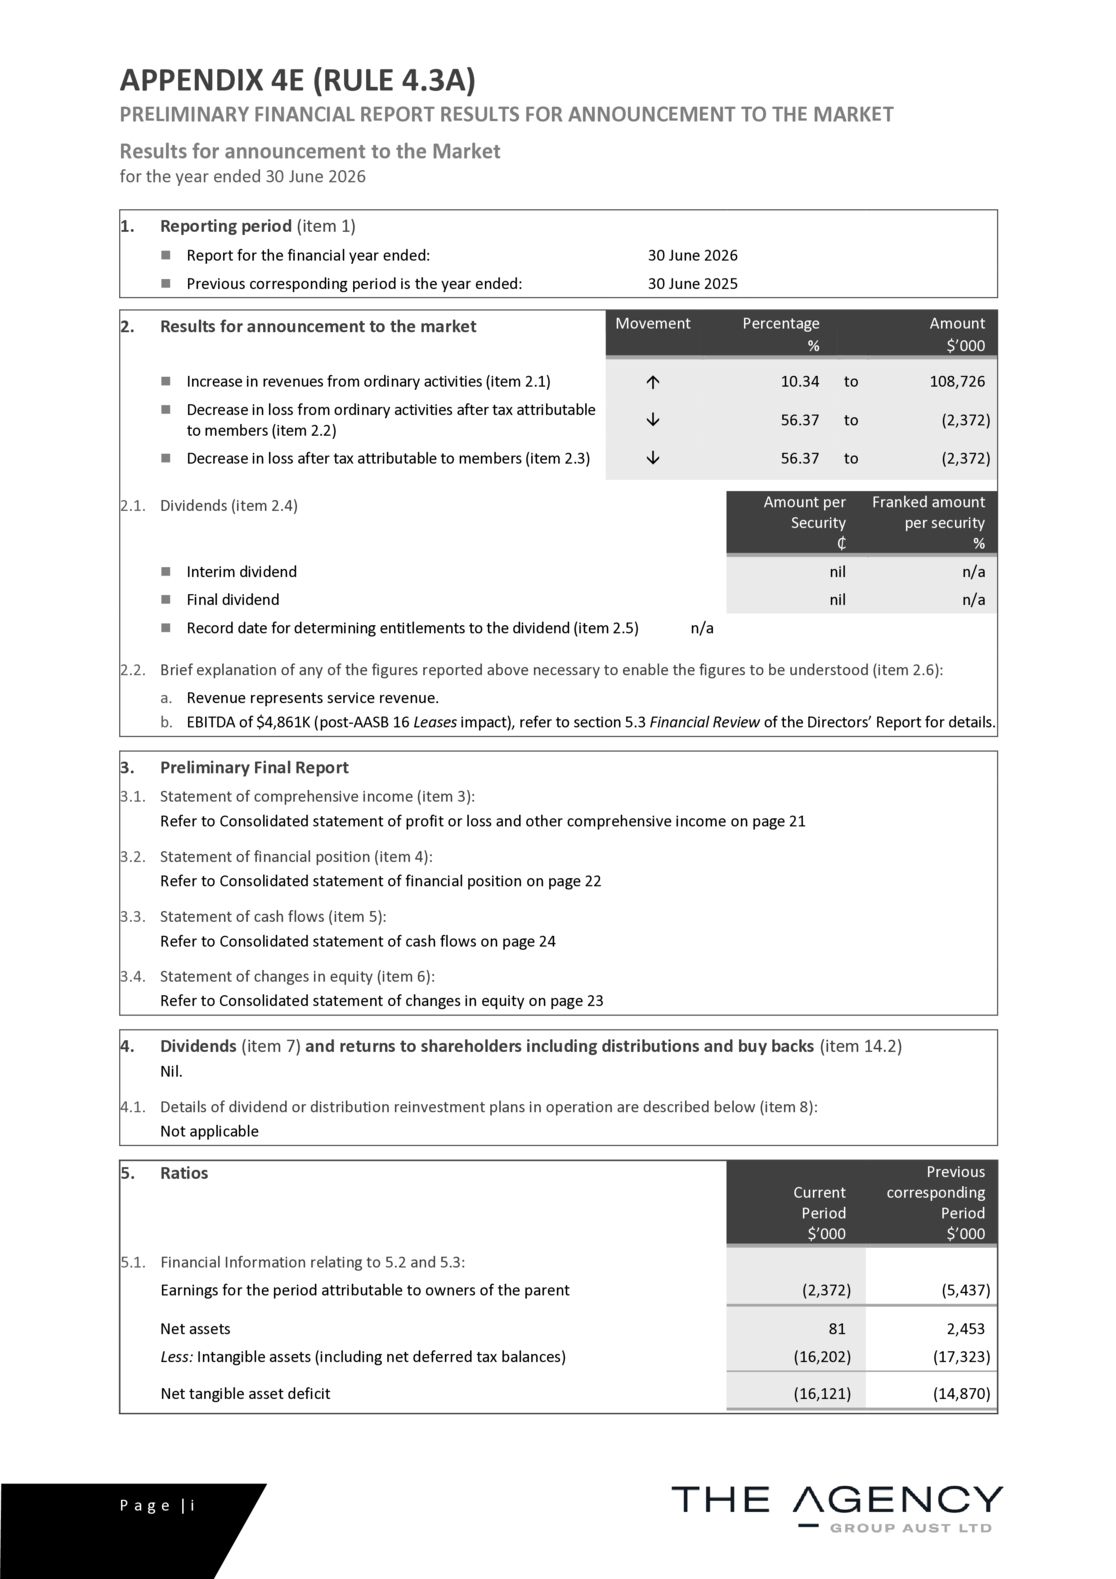
APPENDIX 4E (RULE 4.3A) PRELIMINARY FINANCIAL REPORT RESULTS FOR ANNOUNCEMENT TO THE MARKET Results for announcement to the Market for the year ended 30 June 2026
1. Reporting period (item 1) ◼ Report for the financial year ended: 30 June 2026 ◼ Previous corresponding period is the year ended: 30 June 2025
2. Results for announcement to the market Movement Percentage Amount % $’000
◼ Increase in revenues from ordinary activities (item 2.1) 10.34 to 108,726 ◼ Decrease in loss from ordinary activities after tax attributable 56.37 to (2,372) to members (item 2.2) ◼ Decrease in loss after tax attributable to members (item 2.3) 56.37 to (2,372)
2.1. Dividends (item 2.4) Amount per Franked amount Security per security ₵ % ◼ Interim dividend nil n/a ◼ Final dividend nil n/a ◼ Record date for determining entitlements to the dividend (item 2.5) n/a
2.2. Brief explanation of any of the figures reported above necessary to enable the figures to be understood (item 2.6): a. Revenue represents service revenue. b. EBITDA of $4,861K (post-AASB 16 Leases impact), refer to section 5.3 Financial Review of the Directors’ Report for details.
3. Preliminary Final Report 3.1. Statement of comprehensive income (item 3): Refer to Consolidated statement of profit or loss and other comprehensive income on page 21
3.2. Statement of financial position (item 4): Refer to Consolidated statement of financial position on page 22
3.3. Statement of cash flows (item 5): Refer to Consolidated statement of cash flows on page 24
3.4. Statement of changes in equity (item 6): Refer to Consolidated statement of changes in equity on page 23
4. Dividends (item 7) and returns to shareholders including distributions and buy backs (item 14.2) Nil.
4.1. Details of dividend or distribution reinvestment plans in operation are described below (item 8): Not applicable
5. Ratios Previous Current corresponding Period Period $’000 $’000 5.1. Financial Information relating to 5.2 and 5.3: Earnings for the period attributable to owners of the parent (2,372) (5,437)
Net assets 81 2,453 Less: Intangible assets (including net deferred tax balances) (16,202) (17,323)
Net tangible asset deficit (16,121) (14,870)
P a g e |i
APPENDIX 4E (RULE 4.3A) PRELIMINARY FINANCIAL REPORT RESULTS FOR ANNOUNCEMENT TO THE MARKET Results for announcement to the Market for the year ended 30 June 2026
5 Ratios (cont.) Previous Current corresponding Period Period No. No.
Fully paid ordinary shares 439,575,921 439,575,921
Weighted average number of ordinary shares outstanding during the period used in 439,575,921 435,025,231 calculation of basic earnings per share (EPS)
₵ ₵
5.2. Net tangible assets backing per share (item 9): (3.67) (3.38)
5.3. Earnings per share attributable to owners of the parent (item 14.1): (0.54) (1.25)
As at 30 June 2026, the Group has 1,500,000 unissued shares under options (2025: 1,500,000) and no performance shares on issue (30 June 2025: nil). The Company has deemed all performance rights conditions have been met and the rights vested. Unvested options and performance rights are not considered to be dilutive. In addition, the Group does not report diluted earnings per share on losses generated by the Group. The Group’s unissued shares under option and performance shares were anti-dilutive in both 2026 and 2025.
6. Details of entities over which control has been gained or lost during the period (item 10): 6.1. Control gained over entities ◼ Name of entities (item 10.1) Nil ◼ Date(s) of gain of control (item 10.2) N/A
6.2. Loss of control of entities ◼ Name of entities (item 10.1) Nil ◼ Date(s) of loss of control (item 10.2) N/A 6.3. Contribution to consolidated profit (loss) from ordinary activities after tax by N/A the controlled entities to the date(s) in the current period when control was gained / lost (item 10.3). 6.4. Profit (loss) from ordinary activities after tax of the controlled entities for the N/A whole of the previous corresponding period (item 10.3)
7. Details of associates and joint venture (item 11): ◼ Name of entities (item 11.1) Westvalley Corporation Pty Ltd ◼ Percentage holding in each of these entities (item 11.2) 20% Previous corresponding Current period Period $’000 $’000 ◼ Aggregate share of profits (losses) of these entities (item 11.3) 15 75
8. Any other significant information needed by an investor to make an informed assessment of the entity’s financial performance and financial position (item 12): Refer to Operating and financial review on page 3 of the accompanying Annual Report.
9. The financial information provided in the Appendix 4E is based on the annual report (attached), which has been prepared in accordance with Australian Accounting Standards (item 13).
10. A commentary on the results for the period (item 14): Refer to Operating and financial review on page 3 of the accompanying Annual Report.
11. The preliminary final report has been prepared based on the 30 June 2026 accounts which have been audited by an independent audit firm in accordance with the requirements of section 302 of the Corporations Act 2001 (Cth). (item 15)
P a g e | ii
ABN 52 118 913 232
and its controlled entities
ANNUAL REPORT 30 June 2026
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Corporate directory
Current Directors Andrew Jensen Executive Chairman and Chief Operating Officer Paul Niardone Executive Director Adam Davey Non-executive Director Michael Schaper Non-executive Director Melissa Peters Non-executive Director
Company Secretary Stuart Usher
Registered Office and Head Office Share Registry Street: 68 Milligan Street Automic Pty Ltd PERTH WA 6000 Street: Level 5, 126 Phillip Street Postal: PO Box 7768 Sydney NSW 2000 Cloisters Square WA 6850 Postal: GPO Box 5193 Telephone: +61 (0)8 9204 7955 Sydney NSW 2001 Facsimile: +61 (0)8 9204 7956 Telephone: 1300 288 664 (within Australia) Email: info@theagencygroup.com.au +61 (0)2 9698 5414 (International) Website: theagencygroup.com.au Email: hello@automicgroup.com.au
Auditors Securities Exchange Hall Chadwick WA Audit Pty Ltd Australian Securities Exchange Street: 283 Rokeby Road Street: Level 40, Central Park Subiaco WA 6008 152-158 St Georges Terrace Telephone: +61 (0)8 9426 0666 Perth WA 6000 Telephone: 131 ASX (131 279) (within Australia) Solicitors Telephone: +61 (0)2 9338 0000 Steinepreis Paganin Facsimile: +61 (0)2 9227 0885 Street: Level 4, The Read Buildings Website: www.asx.com.au 16 Milligan Street ASX Code: AU1 Perth WA 6000
P a g e |i
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Contents
◼ Chairman’s letter……………………………………………………………………………………………………………………………………………………. 1 ◼ Directors’ report …………………………………………………………………………………………………………………………………………………….. 3 ◼ Remuneration report ……………………………………………………………………………………………………………………………………………. 11 ◼ Auditor’s independence declaration ……………………………………………………………………………………………………………………….. 20 ◼ Consolidated statement of profit or loss and other comprehensive income…………………………………………………………………. 21 ◼ Consolidated statement of financial position ………………………………………………………………………………………………………….. 22 ◼ Consolidated statement of changes in equity …………………………………………………………………………………………………………… 23 ◼ Consolidated statement of cash flows …………………………………………………………………………………………………………………….. 24 ◼ Notes to the consolidated financial statements ……………………………………………………………………………………………………….. 25 ◼ Consolidated Entity Disclosure Statement ……………………………………………………………………………………………………………….. 67 ◼ Directors’ declaration ……………………………………………………………………………………………………………………………………………. 69 ◼ Independent auditor’s report…………………………………………………………………………………………………………………………………. 70 ◼ Corporate governance statement …………………………………………………………………………………………………………………………… 76 ◼ Additional Information for Listed Public Companies ………………………………………………………………………………………………….. 77
P a g e | ii
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Chairman’s letter
Dear Shareholders,
Record market share. Stronger earnings. A business built for long-term growth.
It is my pleasure to present The Agency Group’s Annual Report for FY2026, a year that marked another important milestone in our evolution. While Australia’s residential property market continued to navigate changing interest rate expectations, affordability pressures and varying conditions across individual states, The Agency demonstrated that a scalable, technology-enabled business model supported by exceptional people can continue to outperform.
Most pleasingly, we continued to grow our share of the national residential property market. According to the Cotality Market Scorecard, The Agency increased its national market share by sales volume to 1.37%, up from 1.30% a year earlier. In an industry where incremental gains in market share are difficult to achieve, this represents another meaningful step forward and reflects the strength of our brand, our agents and our operating model.
Financially, the Group delivered another year of solid progress. Gross Commission Income exceeded $151 million, while revenue increased to $108.7 million. Gross profit continued to improve and EBITDA rose to $1.79 million, representing an increase of almost 60% on the prior year. Importantly, we also significantly reduced our net loss, demonstrating that the investments made over recent years are translating into improved financial performance.
These results were underpinned by continued operational growth across the business. During FY2026, our network expanded to 511 agents nationally, we completed 6,849 properties sold, secured almost 8,000 new listings and continued to strengthen our recurring revenue base through growth in property management, which reached 5,481 properties under management by year end.
While these numbers are encouraging, they tell only part of the story.
The real achievement has been our ability to build a business that is becoming stronger with increasing scale. As we continue to grow our network, our investments in technology, marketing, data analytics and shared services are benefiting a larger number of agents and offices, improving productivity while maintaining cost discipline. This operating leverage positions the Group to continue expanding margins as revenue grows.
Throughout the year we also remained focused on attracting high-quality agents who align with our culture and client-first philosophy. The Agency’s reputation as a premium national brand continues to strengthen, allowing us to recruit experienced professionals who see genuine value in our model. Their success ultimately translates into stronger outcomes for clients, shareholders and the broader business.
Our strategy remains unchanged. We are building Australia’s leading modern real estate business by increasing market share, growing recurring revenue, improving operating efficiency and allocating capital in a disciplined manner. The residential real estate industry remains highly fragmented, providing significant opportunities for a business with a nationally recognised brand and a proven ability to integrate quality agents and businesses successfully.
The final two months of FY2026 also coincided with the Australian Government’s announced changes to negative gearing and capital gains tax arrangements. As is often the case following significant policy reform, the residential property market experienced a period of uncertainty as buyers, sellers and investors sought to understand the implications of the new policy settings. This moderation in market activity continued into the early weeks of FY2027 and provides important context for trading conditions entering the new financial year.
P a g e |1
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Looking ahead, we remain confident in the Group’s trajectory. While we expect the market to continue adjusting to these policy changes in the near term, with our expanding national footprint, growing property management business and continued operational efficiencies, we believe The Agency is well positioned to deliver further improvements in earnings and long-term shareholder value.
On behalf of the Board, I would like to sincerely thank our agents, employees, leadership team, franchise partners and shareholders for their continued commitment and support throughout the year. The progress achieved in FY2026 would not have been possible without their dedication.
While we are proud of what has been accomplished, we believe we are still in the early stages of The Agency’s growth story. We enter FY2027 with strong momentum, increasing scale and confidence that our strategy will continue to create sustainable value for all stakeholders.
ANDREW JENSEN Chairman
P a g e |2
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Directors’ report Your directors present their report on the Group, consisting of The Agency Group Australia Ltd (The Agency or the Company) and its controlled entities (collectively the Group), for the financial year ended 30 June 2026 (FY2026). The Agency is listed on the Australian Securities Exchange (ASX:AU1).
1. Directors The names of Directors in office at any time during or since the end of the year are: ◼ Andrew Jensen Executive Chairman and Chief Operating Officer ◼ Paul Niardone Executive Director ◼ Adam Davey Non-Executive Director ◼ Michael Schaper Non-Executive Director ◼ Melissa Peters Non-Executive Director (appointed 1 May 2026) (collectively the Directors or the Board) Directors have been in office since the start of the financial year to the date of this report unless otherwise stated. For additional information of Directors including details of the qualifications of Directors, please refer to paragraph 6 of this Directors Report.
2. Company secretary The following person held the position of Company Secretary at the end of the financial year:
◼ Stuart Usher Qualifications B.Bus., CPA, Grad Dip CSP, MBA, FGIA, FCIS Experience Mr Usher is a CPA and Chartered Company Secretary with over 25 years of extensive experience in the management and corporate affairs of public listed companies. He holds an MBA from the University of Western Australia and has extensive experience across many industries focusing on Corporate & Financial Management, Strategy & Planning, Mergers & Acquisitions, and Investor Relations & Corporate Governance.
3. Dividends paid or recommended There were no dividends paid or recommended during the financial year ended 30 June 2026.
4. Significant changes in the state of affairs There have been no significant changes in the state of affairs of the Group during the financial year ended 30 June 2026 other than disclosed elsewhere in this Annual Report.
5. Operating and financial review 5.1. Nature of Operations and Principal Activities The principal activity of the Group for the financial year was real estate services and related activities. There were no significant changes in the nature of the Group’s principal activities during the financial year.
5.2. Operations Review a. Key Metrics
ANNUAL GROUP REVENUE ($M) GCI ($M) 120 160 100 140 151.6 108.7 98.5 120 80 125.3 88.0 100 112.5 60 72.7 76.9 80 102.5 95.4 40 60 40 20 20 0 0 FY22 FY23 FY24 FY25 FY26 FY22 FY23 FY24 FY25 FY26
P a g e |3
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Directors’ report
NUMBER OF EXCHANGES NUMBER OF NEW LISTINGS 7,000 10,000 6,849 8,000 6,500 6,663 7,608 7,971 6,000 6,916 6,000 6,239 6,297 6,112 4,000 5,500 5,709 5,734 2,000
5,000 0 FY22 FY23 FY24 FY25 FY26 FY22 FY23 FY24 FY25 FY26
NATIONAL MARKET SHARE 1.50%
1.25% 1.37% 1.30% 1.21% 1.23% 1.00% 0.98% 0.75%
0.50% FY22 FY23 FY24 FY25 FY26
Throughout FY2026, The Agency continued to deliver against its objectives and achieved growth in Number of Exchanges and Annual Group Revenue. The results continue the year-on-year growth that has been achieved for the past seven years. For FY2026, The Agency reported Combined Group Revenue of $108.7 million, a 10% increase year-on-year (FY2025: $98.5 million). The Agency recorded 6,849 properties sold during FY2026, a 2.8% increase from 6,663 properties sold in FY2025. This increase in transaction volumes, along with an increased proportion of sales in higher priced New South Wales, resulted in $9.0 billion of gross property sold, a 21.6% improvement from the FY2025 result of $7.4 billion. The increase in properties sold, along with an increase in contribution from states with higher property prices, assisted in a 21% increase in combined Gross Commission Income (GCI) to $151.6 million (FY2025: $125.3 million). As at 30 June 2026, The Agency consisted of 511 agents, a net increase of 69 agents throughout FY2026 (30 June 2025: 442 Agents). The Agency reported a total portfolio of 5,481 Properties under Management (PuM) as at 30 June 2026. The Company has recently obtained an independent professional valuation of the rent rolls which indicates the market value of these assets to be around $38.10 million (FY2025: $37.41 million). Under International Financial Reporting Standards, the value of internally generated PuM is not held on the balance sheet as an intangible asset. As a result of this, there is significant shareholder wealth held off balance sheet, as only $2.68 million of the $38.10 million Property Management value is held on balance sheet. The Agency’s property management operations delivered $10.54 million in management fees (FY2025: $9.76 million). Overall property management revenue increased to $14.48 million (FY2025: $13.50 million). The expansion of this division continues to provide the Company with the benefits of operating leverage, enhancing efficiency and supporting stronger margins. The Group settlements declined by 1.4% during the year, with a small decrease in transaction volumes from 1,757 in FY2025 to 1,732 in FY2026.
P a g e |4
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Directors’ report
5.3. Financial Review The financial statements have been prepared on a going concern basis, which contemplates the continuity of normal business activity and the realisation of assets and the settlement of liabilities in the ordinary course of business. a. Non-IFRS information The Company reports EBITDA in addition to the Profit after Tax. EBITDA is a financial measure which is not prescribed by Australian Accounting Standards (AAS) and represents the statutory profit under AAS adjusted for specific non-cash and significant items. The Company’s Directors consider EBITDA to reflect the core earnings of the consolidated entity. A reconciliation between EBITDA and profit after income tax for the year ended 30 June 2026 is noted below.
EBITDA calculation FY2026 FY2025 Change Change $’000 $’000 $’000 %
Profit / (loss) after tax (2,372) (5,437) +3,065 +56%
Income tax benefit – – Profit / (loss) before tax (2,372) (5,437) +3,065 +56%
Interest income (53) (51) Depreciation and amortisation 4,733 6,619 Embedded derivative non-cash financing (gains) / costs1 857 679 Interest and finance costs 1,943 2,042 (Loss) / gain financial assets at FVPL – – Profit on sale of assets and lease exit (339) (49) Gain on sale of net assets disposed – – Valuation services – 30 Business acquisition costs non-recurring 107 – Share of profit or loss from equity accounted investments (15) (75)
EBITDA 4,861 3,758 +1,103 +29%
AASB 16 Leases impact2 (3,075) (2,635)
EBITDA (pre-AASB16 Leases impact) 1,786 1,123 + 663 +59% Other key metrics:
◼ Revenue 108,726 98,541 +10,185 +10%
◼ GCI 151,638 125,266 +26,372 +21%
◼ Gross profit 35,679 32,063 +3,616 +11% For FY2026 the Group recorded EBITDA of $4.86 million (FY2025: $3.76 million). After adjusting for the AASB 16 Leases impact, underlying EBITDA for FY2026 was $1.79 million profit. This represents a $0.66 million increase in underlying EBITDA.
The Group generated a net loss after tax for the year of $2.37 million (FY2025: $5.44 million loss). This was primarily impacted by interest and finance costs ($1.94 million), depreciation and amortisation ($4.73 million), and salaries and employment costs ($88.30 million). These items were partially offset by an increase in revenue to $108.73 million.
1 Refer to note 2.2 of the financial statements. 2 AASB 16 Leases was adopted from 1 July 2019. The above demonstrates finance costs and amortisation, which prior to the adoption AASB 16 was recognised as rent expense.
P a g e |5
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Directors’ report
The net assets of the Group have decreased from 30 June 2025 by $2.37 million to $0.08 million at 30 June 2026 (30 June 2025: $2.45 million). Importantly, due to accounting standards, the values of internally generated property management assets are not recorded on the balance sheet. For the year ended 30 June 2026, the Company obtained an independent professional valuation of the rent rolls which indicated the market value of these assets to be $38.10 million (2025: $37.41 million). As a result of the valuation, there is significant shareholder wealth held off balance sheet of $35.42 million (2025: $33.41 million), with only $2.68 million of the $38.10 million valuation being held on balance sheet. This is an increase of $2.01 million compared to the prior year.
The Group’s cash and cash equivalents decreased from 30 June 2025 by $0.82 million to ≈$4.24 million at 30 June 2026 (2025: $5.07 million).
5.4. Key Business Risks The Group is subject to various risk factors. Some of these are specific to its business activities while others are of a more general nature. Individually, or in combination, these risk factors may affect the future operating and financial performance of the Group.
a. People The Agency operates in a highly competitive environment and there is a risk that The Agency may not be able to recruit or retain quality staff to achieve its operational objectives or mitigate succession risk. The Agency mitigates this risk through a structured approach to recruitment, as well as providing competitive remuneration and incentive programs to attract and retain high performing talent across Sales, Property Management, Mortgage Broking, Support staff, and corporate functions.
b. Australian residential real estate market The Agency generates the majority of revenue from the Australian residential real estate market. Revenue is generated in various forms such as Gross Commission Income (GCI) which is produced on the sale of properties; property management commissions are received on collecting rent and associated activities; and commission payments on the arranging of mortgages. The risk of a reduction in sales transaction volumes or prices is a material risk for The Agency and could result from general economic conditions and factors beyond the Group’s control such as housing affordability, employment, interest rates, domestic investor growth and demand, foreign investment and consumer confidence. As different states in Australia have different economic conditions at any one time, The Agency partly mitigates this risk through geographical diversification, operating in 6 states and territories across Australia. c. Reputation and brand The Agency’s reputation and brand may be impacted from both a customer perspective and an investor perspective. The Agency is a young, dynamic brand which is disrupting the existing status quo of selling real estate in Australia. The Agency continues to invest in our customer proposition, using technology, training and processes to enhance our customers and agents experience to ensure a solid scalable platform for growth.
d. IT Systems and cyber risks The Agency’s IT framework is a combination of proprietary systems and Software as a Service Providers. The Agency believes that the combination of these systems provides a competitive advantage and a foundation for a scalable platform for growth. The Agency’s operations are dependent on these systems which individually or collectively could fail or be deliberately targeted which could lead to interruption of service, corruption of data or theft of personal data. The Agency mitigates against these risks through a combination of internal and outsourced IT professionals who maintain both preventative and detective processes and implements controls, including staff training to reduce the risk.
e. Regulatory and legal risk The Australian real estate industry is subject to a broad range of federal, state, and local laws and regulations, including those related to licensing, privacy, consumer protection, anti-money laundering (AML), foreign investment, and tenancy laws. Changes in legislation, regulatory enforcement, or failure to comply with existing obligations may adversely impact operations or financial performance. This includes the Australian Government’s announced changes to negative gearing and capital gains tax arrangements. The Agency manages this risk by maintaining compliance frameworks, engaging legal advisors, and ensuring staff are regularly trained in regulatory obligations. f. Commercial property market cycles The commercial property sector is inherently cyclical and influenced by macroeconomic conditions such as GDP growth, office vacancy rates, business investment, and consumer spending. A downturn in commercial property markets can affect transaction volumes, rental yields, and occupancy levels. The Agency monitors sector-specific trends and diversifies its commercial exposure by property type and geography where possible. P a g e |6
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Directors’ report
g. Interest rate and credit market exposure Interest rates significantly impact both buyer sentiment and investor demand in the real estate sector. Rising interest rates typically reduce borrowing capacity and housing affordability, potentially leading to decreased transaction volumes. Similarly, tighter credit conditions or changes in lending practices from financial institutions could adversely affect residential sales and project marketing performance. The Agency monitors interest rate trends and engages with financial institutions and mortgage brokers to assess market impacts.
h. Environmental and climate-related risk Real estate businesses are increasingly exposed to risks associated with climate change and environmental regulations. This includes physical risks (e.g. bushfires, flooding, extreme weather affecting properties under management or development), as well as transitional risks arising from evolving environmental regulations and changing investor and consumer expectations. The Agency acknowledges this risk and is exploring strategies to manage exposure, including supporting sustainable developments and conducting risk assessments as part of due diligence processes.
i. Market competition and disruption The real estate industry remains highly fragmented and competitive, with new entrants, digital platforms, and alternative business models emerging. There is a risk that new or existing competitors may adopt disruptive pricing, technology, or service strategies that erode The Agency’s market share or margins. The Agency continues to invest in innovation, agent enablement, and differentiated customer service to stay competitive.
j. Capital management and liquidity risk As a listed entity, The Agency is subject to capital market fluctuations that may impact its ability to raise funds, maintain sufficient working capital, or meet financial obligations. Volatility in equity markets or broader economic conditions may limit access to funding for expansion or operations. The Agency maintains prudent liquidity management practices and regularly monitors cash flow and debt levels.
5.5. Environmental Regulations The Group’s operations are not subject to any significant environmental regulations in the jurisdictions it operates in.
5.6. Events Subsequent to Reporting Date There are no other significant after balance date events that are not covered in this Directors’ Report or within the financial statements as disclosed in note 16 Events subsequent to reporting date on page 59.
5.7. Future Developments, Prospects and Business Strategies The Group’s strategy is to build a leading national residential real estate business by increasing market share, expanding recurring revenue streams and driving greater operating efficiency.
The Agency’s direct engagement model enables agents to operate within a national platform supported by centralised administration, marketing, technology and compliance functions, reducing the cost and administrative burden associated with operating a traditional office-based agency.
Future growth is expected to be driven by the continued recruitment of experienced agents in existing markets, disciplined expansion into new regions and further growth in recurring and complementary revenue streams. In particular, the Group intends to continue expanding its property management portfolio, providing a growing source of recurring revenue that is less directly exposed to residential sales transaction volumes.
As the network expands, the Group expects to benefit from increased operating leverage through its centralised platform and shared services infrastructure, supporting further improvements in productivity and margins.
The Australian residential real estate industry remains highly fragmented, providing opportunities for the Group to attract established agents and principals of independent agencies seeking the benefits of a larger platform without the administrative requirements of operating their own business. The Group will also continue to assess strategic partnerships and adjacent revenue opportunities that complement its existing property management, mortgage broking and conveyancing operations.
Other than as disclosed in this report, the Directors are not aware of any likely developments that would materially affect the Group’s future results. Further information has not been included where the Directors consider that disclosure would be likely to result in unreasonable prejudice to the Group.
P a g e |7
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Directors’ report
6. Information relating to the Directors ◼ Mr Andrew Jensen Executive Chairman and Chief Operating Officer Non-independent Qualifications FIPA, MAICD Experience Mr Jensen previously held the position of Chief Financial Officer for International and leading Australian Companies, which will greatly assist the Company in its next phase of national growth under the two prominent brands of The Agency and Sell Lease Property. Mr Jensen has strong commercial, strategic, and M&A experience and has financially led companies engaged in various fields including real estate, financial services, telecommunications, and the franchising sectors both in Australia and Internationally. He is an accomplished CFO with over 19 years’ experience in senior finance and management roles. Previously, Mr Jensen was the CFO and Director of Australasia’s largest real estate group Ray White, with over $20 billion in annual sales and one of Australia’s largest independent mortgage broking businesses Loan Market. He has also been the CFO of VGC Food Group Pty Ltd, a private diversified manufacturing and franchising group. Mr Jensen was also CFO and COO of Digicel PNG (Papua New Guinea) part of Digicel Group Limited (Digicel), one of the South Pacific’s largest and most successful telecommunications companies. He is also a fellow of the Institute of Public Accountants and member of the Australian Institute of Company Directors.
Interest in Company equity Indirect 2,903,492 Ordinary Shares Directorships in listed None entities (past three years)
◼ Mr Paul Niardone Executive Director Non-independent Qualifications MBA, BA B Experience Mr Niardone was one of the founders of The Agency and until January 2022 was the Managing Director but has opted to take up a more operational role as an Executive Director. He was formerly executive director and founder of Professional Public Relations (WA), the largest PR and communications firm in the State until he sold the business to WPP. Mr Niardone has experience in marketing and strategic planning for clients in both Government and the private sector. With a degree in Politics and Industrial Relations and a Master in Business Administration, he started his career in the Department of Cabinet and Parliamentary Services. He was appointed inaugural Manager of the Peel Region Business Enterprise Centre and was then appointed as the first Marketing Manager for the entire Enterprise Centre Network comprising 36 centres throughout WA. Mr Niardone’s marketing skills were recognised by Westpac in its decision to appoint him as one of the first Business Banking Managers in Australia without a banking background. His career to date has provided him with a unique opportunity to gain experience, insights and contacts in a wide range of industries at the CEO and Board level. He has sat on the boards of a number of public and private companies and not for profit organisations.
Interest in Company equity Indirect 14,327,008 Ordinary Shares Directorships in listed MTM Critical Metals Limited (ASX:MTM) (appt. 15 April 2024) entities (past three years)
P a g e |8
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Directors’ report
◼ Mr Adam Davey Non-executive Director Non-independent Qualifications and Mr Davey is a Director of Wealth Management at Canaccord Genuity Financial Limited. experience Mr Davey’s expertise spans over 36 years and includes capital raising (both private and public), mergers and acquisition, ASX listings, asset sales and purchases, transaction due diligence and director duties. Mr Davey has been involved in significantly growing businesses in both the industrial and mining sector. This has been achieved through holding various roles within different organisations, including Chairman, Managing Director, Non-executive director, major shareholder or corporate adviser to the board. Mr Davey is also the Chairman of Adult and Teen Challenge Foundation, which supports the work of Adult and Teen Challenge helping families breaking free from the bondage of addiction.
Interest in Company equity Indirect 1,700,001 Ordinary Shares Directorships in listed Painchek Ltd entities (past three years)
◼ Dr Michael Schaper Non-executive Director Non-independent Qualifications Ph.D. (Management), M.Comm., Grad.Dip (Business), BA B Experience Dr Schaper brings a wealth of regulatory and governance experience, with over 10 years as the Deputy Chair of the Australian Competition and Consumer Commission (ACCC) between 2008- 2018, which included responsibility for overseeing franchising regulation. After his time at the ACCC, Dr Schaper chaired AFIA’s Buy Now, Pay Later (BNPL) code of conduct compliance committee. His extensive experience in these areas is particularly valuable for The Agency, as most participants in the real estate sector are franchise-based, and The Agency has strong connections to financial products, such as mortgages and Vendor Paid Advertising (VPA). Currently a national board member of the Australian Institute of Company Directors (AICD), Dr Schaper also serves as the Chair of its National Education Advisory Committee, which oversees the highly regarded Company Directors Course. His leadership in corporate governance education further reinforces his suitability for this role. Dr Schaper’s expertise in regulatory frameworks and financial products will significantly enhance the company’s strategy development, M&A activities, and corporate governance, ensuring the company is well positioned for continued growth and expansion. Dr Schaper’s extensive board and governance experience spans across a wide range of sectors, including startups, government bodies, and not-for-profit organisations (NFPs). He is currently the Chair of Energy Consumers Australia, and the Chair of the Energy & Water Ombudsman of Western Australia.
Interest in Company equity Direct 367,134 Ordinary Shares Directorships in listed None entities (past three years)
◼ Ms Melissa Peters Non-executive Director Non-Independent Qualifications B.Econ (UWA) B Experience Ms Peters is the Managing Director of Peters Investments Pty Ltd, where she leads the strategic direction, business governance, operational oversight and day-to-day management of a diversified range of interests across property investment and development, listed and private equity investments, agribusiness and automotive retail. Ms Peters was formerly the Marketing, Advertising and Events Manager for the Peters Investments Pty Ltd’s group of Luxury Motor Vehicle Dealerships, which included such brands as BMW, Mini, and Honda, and brings over 25 years of experience in brand management, business development, customer relationship management and team performance management.
P a g e |9
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Directors’ report
Interest in Company equity Indirect 134,000,000 Ordinary Shares (see 15.8.a(2) for more detail) Directorships in listed None entities (past three years)
7. Meetings of Directors and committees During the financial year, 11 meetings of Directors were held. Attendances by each Director during the year are stated in the following table. DIRECTORS’ REMUNERATION AND FINANCE AND OPERATIONS AUDIT MEETINGS NOMINATION COMMITTEE COMMITTEE COMMITTEE Number Number Number Number eligible to Number eligible to Number eligible to Number eligible to Number attend Attended attend Attended attend Attended attend Attended Andrew Jensen 11 11 At the date of this report, Remuneration and Nomination Committee, the Audit and Finance and Paul Niardone 11 11 Operations Committees comprise the full Board of Directors. The Directors believe the Company Adam Davey 11 11 is not currently of a size nor are its affairs of such complexity as to warrant the establishment of Michael Schaper 11 11 these separate committees. Accordingly, all matters capable of delegation to such committees are considered by the full Board of Directors. Melissa Peters 2 2
8. Indemnifying officers or auditor 8.1. Indemnification The Company has paid premiums to insure each of the current and former Directors and officers against liabilities for costs and expenses incurred by them in defending any legal proceedings arising out of their conduct while acting in the capacity of Director or Officer of the Company, other than conduct involving a wilful breach of duty in relation to the Company. The Company has not given any further indemnity or entered into any other agreements to indemnify, or pay, or agree to pay insurance premiums. No indemnities have been given or insurance premiums paid, during or since the end of the period, for any person who is or has been an auditor of the Company.
8.2. Insurance premiums The contract of insurance prohibits disclosure of the nature of liability and the amount of the premium.
9. Options 9.1. Unissued shares under option At the date of this report, the unissued ordinary shares of the Company under option (listed and unlisted) are as follows: Grant Date Date of Expiry Exercise Price Number under Vested and $ Option Exercisable 30 Nov 2023 30 Nov 2026 0.050 1,500,000 1,500,000 1,500,000 1,500,000
No person entitled to exercise the option has or has any right by virtue of the option to participate in any share issue of any other body corporate. 9.2. Shares issued on exercise of options No shares have been issued by the Company during the financial year as a result of the exercise of options (2025: nil). No shares were issued on the conversion of performance rights (2025: 11,000,000).
10. Non-audit services During the year, Hall Chadwick WA Audit Pty Ltd (Hall Chadwick), the Company’s and Group’s auditor did not provide non-audit services (2025: nil), in addition to their statutory audits. Details of remuneration paid to the auditor can be found within the financial statements at note 20 Auditor’s Remuneration on page 61.
P a g e | 10
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Directors’ report Where non-audit services are provided by Hall Chadwick, the Board has established certain procedures to ensure that the provision of non-audit services is compatible with, and does not compromise, the auditor independence requirements of the Corporations Act 2001 (Cth). These procedures include: ◼ non-audit services will be subject to the corporate governance procedures adopted by the Company and will be reviewed by the Board to ensure they do not impact the integrity and objectivity of the auditor; and ◼ ensuring non-audit services do not involve reviewing or auditing the auditor’s own work, acting in a management or decision- making capacity for the Company, acting as an advocate for the Company or jointly sharing risks and rewards.
11. Proceedings on behalf of the Company No person has applied to the Court under section 237 of the Corporations Act 2001 (Cth) for leave to bring proceedings on behalf of the Company, or to intervene in any proceedings to which the Company is a party, for the purpose of taking responsibility on behalf of the Company for all or part of those proceedings. No proceedings have been brought or intervened in on behalf of the Company with leave of the Court under section 237 of the Corporations Act 2001 (Cth).
12. Rounding of amounts The amounts contained in this report have been rounded to the nearest thousand dollars under the option available to the Company under Australian Securities and Investments Commission Corporations (Rounding in Financial/Directors’ Reports) Instrument 2016/191 dated 24 March 2016.
13. Corporate Governance In recognising the need for the highest standards of corporate behaviour and accountability, the Directors of The Agency support and have substantially adhered to the best practice recommendations set by the ASX Corporate Governance Council. For a detailed analysis of the Company’s Corporate Governance Policies, visit the corporate governance section of our website at www.investors.theagency.com.au/corporate-governance.
14. Auditor’s independence declaration The lead auditor’s independence declaration under section 307C of the Corporations Act 2001 (Cth) for the year ended 30 June 2026 has been received and can be found on page 20 of the annual report. 15. Remuneration report (audited) This report outlines the remuneration arrangements in place for Directors and key management personnel of the Company for the year ended 30 June 2026. The information in this remuneration report has been audited as required by section 308(3C) of the Corporations Act 2001 (Cth).
15.1. Key management personnel (KMP) This remuneration report details the remuneration arrangements for KMP who are defined as those persons having authority and responsibility for planning, directing and controlling the major activities of the Company and the Group, directly or indirectly, including any director (whether Executive or otherwise) of the parent company. KMP comprise the Directors of the Company and key executive personnel: ◼ Andrew Jensen Executive Chairman and Chief Operating Officer ◼ Paul Niardone Executive Director ◼ Adam Davey Non-Executive Director ◼ Michael Schaper Non-Executive Director ◼ Melissa Peters Non-Executive Director (appointed 1 May 2026) ◼ Other KMP: Matt Lahood CEO – Real Estate ◼ Former KMP included within comparative information: Geoff Lucas Managing Director and Chief Executive Officer (CEO) (terminated 6 August 2024)
P a g e | 11
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Directors’ report
15. Remuneration report (audited)
15.2. Principles used to determine the nature and amount of remuneration a. Remuneration Policy The remuneration policy of The Agency has been designed to align director and management objectives with shareholder and business objectives by providing a fixed remuneration component, and offering specific long-term incentives, based on key performance areas affecting the Group’s financial results. The Board believes the remuneration policy to be appropriate and effective in its ability to attract and retain the best management and directors to run and manage the Group, as well as create goal congruence between directors, executives and shareholders. The remuneration policy, setting the terms and conditions for the executive directors and other senior executives, was developed by the Board. All remuneration paid to Directors and executives is valued at the cost to the Company and expensed. The Board policy is to remunerate non-executive Directors at the lower end of market rates for comparable companies for time, commitment, and responsibilities. The maximum aggregate amount of fees that can be paid to non-executive Directors is subject to approval by shareholders at the Annual General Meeting (AGM). Fees for non-executive Directors are not linked to the performance of the Group. b. Performance Conditions Linked to Remuneration The Group seeks to establish and maintain The Agency Group Australia Limited Performance Rights Plan (Plan) to provide ongoing incentives to any full time or part-time employee, consultant or any person nominated by the Board (including director or company secretary of the Company who holds salaried employment with the Company on a full or part time basis) (Eligible Participants) of the Company. The Plan was adopted to allow Eligible Participants to be granted Performance Rights to acquire shares in the Company. The objective of the Plan is to provide the Company with a remuneration mechanism, through the issue of Company securities, to motivate and reward the performance of Eligible Participants in achieving specified performance milestones within a specified performance period. The Board will ensure that the performance milestones attached to the securities issued pursuant to the Plan are aligned with the successful growth of the Company’s business activities.
c. Remuneration structure In accordance with best practice corporate governance, the structure of Non-Executive Director and Executive compensation is separate and distinct. (1) Non-executive director remuneration The Board seeks to set aggregate remuneration at a level which provides the Company with the ability to attract and retain directors of the highest calibre, whilst incurring a cost which is acceptable to shareholders. The Constitution and the ASX Listing Rules specify that the aggregate remuneration of non‐executive directors shall be determined from time to time by a general meeting. An amount not exceeding the amount determined is then divided between the Directors as agreed. The latest determination was at the Annual General Meeting held on 29 April 2016 when shareholders approved an aggregate remuneration of $250,000 per year. The Board considers advice from external consultants when undertaking the annual review process. (2) Executive remuneration Senior executives, including Executive Directors, are engaged under the terms of individual employment contracts. Such contracts are based upon standard terms drafted by the Company’s lawyers. Base salary/consulting fees are set to reflect the market salary for a position and individual of comparable responsibility and experience. Base salary/consulting fees are regularly compared with the external market and during recruitment activities generally. It is the policy of the Company to maintain a competitive salary structure to ensure continued availability of experienced and effective management and staff. Executives are prohibited from entering into transactions or arrangements which limit the economic risk of participating in unvested entitlements. Details of the nature and amount of each element of each Director, including any related company and each KMP are set out below.
P a g e | 12
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Directors’ report
15. Remuneration report (audited) d. Contractual arrangements of members of KMP (1) Executive Services Agreement (ESA) – Paul Niardone Mr Niardone entered into an ESA, revised on 11 January 2019, with the Company to be employed as Managing Director upon and subject to the terms and conditions of the ESA. On 28 January 2022, Mr Niardone stepped down as Managing Director and was appointed Executive Director, focussed on continuing to grow Western Australian business, national growth of emerging SLP business, expansion of financial services division and advancing a range of technology focused property technology opportunities. The key terms of this agreement are disclosed below: (A) Remuneration (i) Mr Niardone will receive a salary of $390,000 per year, exclusive of superannuation, which will be reviewed annually by the Company (Salary), plus an annual Director fee of $48,000 (as revised on 28 January 2022). The Company will make employer superannuation contributions on behalf of Mr Niardone. (ii) Mr Niardone, on the same basis of other Directors, may participate in a short-term and/or long-term incentive plans whether involving the issue of shares, options, rights or other incentives to Mr Niardone to remain at the Company and achieve the Company’s targets. Any such incentives will be governed by the relevant plan or scheme adopted by the Company. (iii) The Company paid operating lease payments for a motor vehicle, on behalf of Mr Niardone, in the amount of $23,548 for the year. (iv) The Company shall provide to Mr Niardone, at its own cost, life insurance protection on similar terms to the life insurance protection currently offered by the Company. This amounted to $96,349 for the year. (v) The Company will reimburse Mr Niardone for all reasonable travelling intra/interstate or overseas, accommodation, and general expenses incurred in the performance of all duties in connection with the business of the Company and its related bodies corporate. (vi) Mr Niardone is entitled to all leave in accordance with the National Employment Standard (NES) and Western Australian long service leave legislation. (B) Termination by the Company without reason The Company may at its sole discretion terminate employment by giving twelve months’ written notice and, at the end of that notice period, making a payment to Mr Niardone equal to the salary payable over a twelve-month period. The Company may elect to pay Mr Niardone the equivalent of the twelve months’ salary and dispense with the notice period (as revised on 11 January 2019). (C) Termination by Mr Niardone Mr Niardone may at his sole discretion terminate the Employment in the following manner: (i) if at any time the Company commits any serious or persistent breach of any of the provisions contained in the ESA and the breach is not remedied within 28 days of receipt of written notice from Mr Niardone to the Company to do so, by giving notice effective immediately; or (ii) by giving three months’ written notice to the Company. (2) ESA – Matthew Lahood 1 Mar 2024 (A) Remuneration (i) Mr Lahood will receive a salary of $650,000 per year, exclusive of superannuation, which will be reviewed annually by the Company (Salary). See also (B) below. (ii) In addition, the Company may at any time during the term of the ESA pay Mr Lahood a performance-based bonus over and above his salary. In determining the extent of any performance-based bonus, the Company shall take into consideration the key performance indicators of Mr Lahood and the Company, as the Company may set from time to time, and any other matter that it deems appropriate. (iii) The Company will make employer superannuation contributions on behalf of Mr Lahood. (iv) The Company will reimburse Mr Lahood for all reasonable travelling intra/interstate or overseas, accommodation, and general expenses incurred in the performance of all duties in connection with the business of the Company and its related bodies corporate. (v) Mr Lahood is entitled to all leave in accordance with the NES.
P a g e | 13
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Directors’ report
15. Remuneration report (audited) (B) Short-term Incentives (i) Mr Lahood may receive short term incentives based on agent recruitment and East Coast GCI targets. Mr Lahood is only entitled to any short-term incentives should Group EBITDA exceed $2 million, for the period 1 July 2025 to 30 June 2026. (ii) Mr Lahood will be entitled to a $20,000 plus GST advance monthly to be used to offset against the above incentives. (C) Termination by the Company without reason The Company may at its sole discretion terminate employment by giving three months’ written notice and, at the end of that notice period, making a payment to Mr Lahood equal to the salary payable over a five-month period. The Company may elect to pay Mr Lahood the equivalent of six months’ salary and dispense with the notice period. (D) Termination by Mr Lahood Mr Lahood may at his sole discretion terminate the Employment in the following manner: (i) if at any time the Company commits any serious or persistent breach of any of the provisions contained in the ESA and the breach is not remedied within 28 days of receipt of written notice from Mr Lahood to the Company to do so, by giving notice effective immediately; or (ii) by giving three months’ written notice to the Company.
(3) Letter of Appointment – Adam Davey On 16 August 2016, Mr Davey executed a letter of appointment as non-executive Director of the Company: (A) Term Mr Davey’s service commenced on the date of completion of the acquisition of Ausnet Real Estate Services Pty Ltd by the Company and will cease when he resigns, retires or is removed from office in accordance with the Company’s constitution or the Corporations Act 2001 (Cth). (B) Fee Mr Davey will be paid a fee of $60,000 per annum (adjusted from $48,000 per annum from December 2024) for his role as a non-executive Director of the Company. Any fees paid to Mr Davey will in any event be subject to annual review by the Board of the Company and approval by Shareholders (if required). The Company will reimburse Mr Davey for all reasonable expenses incurred in performing his duties.
(4) Letter of Appointment – Andrew Jensen On 15 February 2019, Mr Jensen executed a letter of appointment as non-executive Director of the Company. (A) Term Mr Jensen’s service commenced on 18 February 2019, and will cease when he resigns, retires or is removed from office in accordance with the Company’s constitution or the Corporations Act 2001 (Cth). (B) Fee Mr Jensen will be paid a fee of $60,000 per annum for his role as a Director of the Company. Any fees paid to Mr Jensen will in any event be subject to annual review by the Board of the Company and approval by Shareholders (if required). The Company will reimburse Mr Jensen for all reasonable expenses incurred in performing his duties.
(5) Letter of Appointment – Michael Schaper On 1 December 2024, Dr Schaper executed a letter of appointment as non-executive Director of the Company. (A) Term Dr Schaper’s service commenced on 1 December 2024, and will cease when he resigns, retires or is removed from office in accordance with the Company’s constitution or the Corporations Act 2001 (Cth). (B) Fee Dr Schaper will be paid a fee of $60,000 per annum including superannuation for his role as a non-executive Director of the Company. Any fees paid to Dr Schaper will in any event be subject to annual review by the Board of the Company and approval by Shareholders (if required). The Company will reimburse Dr Schaper for all reasonable expenses incurred in performing his duties.
(6) Letter of Appointment – Melissa Peters On 1 May 2026, Ms Peters executed a letter of appointment as non-executive Director of the Company. (A) Term Ms Peters’ service commenced on 1 May 2026, and will cease when she resigns, retires or is removed from office in accordance with the Company’s constitution or the Corporations Act 2001 (Cth).
P a g e | 14
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Directors’ report
15. Remuneration report (audited) (B) Fee Ms Peters will be paid a fee of $60,000 per annum including superannuation for her role as a non-executive Director of the Company. Any fees paid to Ms Peters will in any event be subject to annual review by the Board of the Company and approval by Shareholders (if required). The Company will reimburse Ms Peters for all reasonable expenses incurred in performing her duties.
(7) Executive Services Agreement (ESA) – Andrew Jensen Mr Andrew Jensen entered into an ESA with the Company to be employed as Chief Operating Officer upon and subject to the terms and conditions of the ESA. The key terms of this agreement are disclosed below: (A) Remuneration (i) Mr Jensen will receive a salary of $455,000 per year (effective 1 March 2026), exclusive of superannuation, which will be reviewed annually by the Company (Salary). The Company will make employer superannuation contributions on behalf of Mr Jensen. (ii) Mr Jensen will continue to receive a director’s fee as detailed in (4) above. (iii) In addition, the Company may at any time during the term of the ESA pay Mr Jensen a performance-based bonus over and above his salary. In determining the extent of any performance-based bonus, the Company shall take into consideration the key performance indicators of Mr Jensen and the Company, as the Company may set from time to time, and any other matter that it deems appropriate. (iv) The Company will reimburse Mr Jensen for all reasonable travelling intra/interstate or overseas, accommodation, and general expenses incurred in the performance of all duties in connection with the business of the Company and its related bodies corporate. (v) Mr Jensen is entitled to all leave in line with the NES and Western Australian long service leave legislation. (B) Termination by the Company without reason The Company may at its sole discretion terminate employment by giving three months’ written notice and, at the end of that notice period, making a payment to Mr Jensen equal to the salary payable over a three-month period. The Company may elect to pay Mr Jensen six months’ salary and dispense with the notice period (C) Termination by Mr Jensen Mr Jensen may at his sole discretion terminate the Employment in the following manner: (i) if at any time the Company commits any serious or persistent breach of any of the provisions contained in the ESA and the breach is not remedied within 28 days of receipt of written notice from Mr Jensen to the Company to do so, by giving notice effective immediately; or (ii) by giving two months’ written notice to the Company. (8) Employment Agreement (EA) – Geoff Lucas Mr Geoff Lucas entered into an EA, commencing on 29 March 2021, with the Company to be employed as Chief Executive Officer upon and subject to the terms and conditions of the EA. On 28 January 2022, Mr Lucas was appointed Managing Director of the Company. Mr Lucas’ employment was terminated on 6 August 2024. Key EA terms were: • Salary Package: $550,000 inclusive of superannuation, plus short and long-term incentives subject to KPIs approved by the Board. • Leave provisions: In accordance with applicable legislation. • Equity issues: On commencement, Mr Lucas was issued 30 million unlisted options (10 million each at 5c, 7.5c and 10c, vesting progressively over the first two years of employment). All options have since expired or lapsed on termination. • Termination: Following the probationary period, either party could terminate on six months’ written notice, with standard summary termination provisions. e. Voting and comments made at the Company’s 2025 Annual General Meeting (AGM) At the AGM held on 21 November 2025, on a poll the Company received 182,865,281 (93.4%) For votes and 12,950,879 (6.6%) Against votes and 15,150 abstentions on its remuneration report for the 2025 financial year. The Group did not employ a remuneration consultant during the year.
P a g e | 15
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Directors’ report
15. Remuneration report (audited) 15.3. Performance-based remuneration a. The following table provides employment details of persons who were, during the financial year, members of KMP of the Group. The table also illustrates the proportion of remuneration that was performance based and the proportion of remuneration received in the form of options. Position Held as at Contract Proportions of Elements of Proportions of Elements of Total Group KMP 30 June 2026 and any Commencement / Remuneration Related to Performance Remuneration Not Related change during the Termination Date to Performance year Non-salary Fixed Salary/ Fixed Salary/ Cash-based Options / Fees – cash Fees – share- Incentives Shares Rights based based % % % % % % Andrew Jensen Executive Chairman Appt. 18.02.2019 (Dir) 14 – – 86 – 100 and COO Appt. 1.02.2020 (COO) Paul Niardone Executive Director Appt. 19.12.2016 11 – – 89 – 100 Adam Davey Non-Executive Appt. 19.12.2016 25 – – 75 – 100 Director Michael Schaper Non-Executive Appt. 1.12.2024 – – – 100 – 100 Director Melissa Peters Non-Executive Appt. 1.05.2026 – – – 100 – 100 Director Matthew Lahood CEO – Real estate Appt. 17.02.2019 – – – 100 – 100
b. Statutory performance indicators The Group aims to align our executive remuneration to our strategic and business objectives and the creation of shareholder wealth. Reported below are measures of the Group’s financial performance over the last five years as required by the Corporations Act 2001 (Cth). However, these are not necessarily consistent with the measures used in determining the variable amounts of remuneration to be awarded to KMPs. As a consequence, there may not always be a direct correlation between the statutory key performance measures and the variable remuneration awarded. 2026 2025 2024 2023 2022
Profit or (loss) for the year attributable to (2,372) (5,437) (4,889) (4,321) 1,588 owners of the Company ($’000) Basic earnings per share (cents) (0.54) (1.25) (1.14) (1.01) 0.37 Dividend payments ($) Nil Nil Nil Nil Nil Dividend payout ratio (%) N/A N/A N/A N/A N/A Share price ($) 0.026 0.021 0.020 0.026 0.037 Increase/(decrease) in share price (%) 23.81 5.00 (23.08) (29.73) (26.00)
15.4. Directors and KMP remuneration Details of the nature and amount of each element of the remuneration of each of the KMP of the Company for the year ended 30 June 2026 are set out in the following tables and represent the components of the current year and comparative year remuneration expenses for each member of KMP of the Group. Such amounts have been calculated in accordance with Australian Accounting Standards. Bonuses paid during the year were based on the achievement of agreed key performance indicators.
P a g e | 16
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Directors’ report
15. Remuneration report (audited) 2026 – Group Short-term benefits Post- Long-term Termination Equity-settled share- Total Group KMP employment benefits benefits based payments benefits Salary, fees, Profit share Non- Other Super- Other Shares Options / and leave & bonuses monetary annuation Perf. Equity $ $ $ $ $ $ $ $ $ $ Andrew Jensen 445,001 75,000 – – 30,000 – – – – 550,001 Paul Niardone 438,000 75,000 – 119,897 30,000 – – – – 662,897 Adam Davey 60,000 20,000 – – – – – – – 80,000 Michael Schaper 53,571 – – – 6,429 – – – – 60,000 Melissa Peters(1) 8,929 – – – 1,071 – – – – 10,000 Matthew Lahood (2) 958,032 – – 36,000 30,000 – – – – 1,024,032
1,963,533 170,000 – 155,897 97,500 – – – – 2,386,930 (1) Ms Peters was appointed on 1 May 2026. (2) Included in Salary, fees, and leave for Mr Lahood is an amount of $240,000 in respect to recruitment incentives, and $104,037 in leave cashed out. 2025 – Group Short-term benefits Post- Long-term Termination Equity-settled share- Total Group KMP employment benefits benefits based payments benefits Salary, fees Profit share Non- Other Super- Other Share Options / and leave & bonuses monetary annuation Perf. Equity $ $ $ $ $ $ $ $ $ $ Andrew Jensen 410,002 – – – 29,932 – – – – 439,934 Paul Niardone 448,000 – – 67,859 29,932 – – – – 545,791 Adam Davey(1) 55,000 – – 35,000 – – – – – 90,000 Michael Schaper 31,390 – – – 3,610 – – – – 35,000 Matthew Lahood(2) 853,995 – – 36,000 29,932 – – – – 919,927 Geoff Lucas(3) 48,695 – – – 5,600 – 275,000 – – 329,295
1,847,082 – – 138,859 99,006 – 275,000 – – 2,359,947 (1) Included in Other short-term benefits for Mr Davey is an amount $35,000 in respect to additional services performed for the Company. (2) Included in Salary, fees, and leave for Mr Lahood is an amount of $240,000 in respect to recruitment incentives. (3) Mr Lucas’ employment was terminated on 6 August 2024.
15.5. KMP Loans As at 30 June 2026, an amount of $355,701 was advanced to Mr Lahood (2025: $559,291), with the following terms: ◼ Principal Sum Up to $650,000 ◼ Loan Commencement 27 October 2021 ◼ Interest Rate 8% per annum (after 12 months from 1 November 2023) ◼ Default Interest Rate Interest Rate above plus 5% per annum ◼ Securities Any future sales commissions and future income and wages as per EA entitlements ◼ Instalment Date Amount is due on final repayment date or when any due amounts are payable on STI payments and sales commissions from property sales that are due. Discretional payments during the term can also be paid ◼ Repayment Date 31 December 2026
P a g e | 17
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Directors’ report
15. Remuneration report (audited)
15.6. Share-based compensation The Group believes that encouraging its directors and executives to become shareholders is the best way of aligning their interests with those of its shareholders. At present the Group does not have an active employee share option plan. There were no equity instruments issued during the year to Directors as a result of options exercised that had previously been granted as compensation.
a. Securities received that are not performance-related No members of KMP are entitled to receive securities that are not performance-based as part of their remuneration package. b. Options and Rights Granted as Remuneration No options were granted to KMP during the current financial year (2025: nil). c. Rights Granted as Remuneration No rights were granted to KMP during the current financial year (2025: 11,000,000 performance rights were converted on 28 November 2024).
15.7. Other transactions with KMP and or their Related Parties a. Some Directors or former Directors of the Group hold or have held positions in other companies, where it is considered they control or significantly influence the financial or operating policies of those entities. During the year, no such entities provided services to the Group (2025: $nil). b. As disclosed in note 5.7.3, the Company issued 5,000,000 convertible notes to Peters Investments Pty Ltd (Peters Investments), a related party of the Company. Peters Investments holds 30.48% of the issued ordinary share capital of the Company, and Ms Melissa Peters, managing director of Peters Investments, was appointed a Director of the Company on 1 May 2026 and is accordingly a member of the Group’s key management personnel from that date. The carrying value of the note was $5,532,800 (2025: 4,292,633). There have been no other transactions in addition to those described in the tables above or as detailed in note 18 Related party transactions.
15.8. KMP equity holdings of The Agency Group Australia Ltd held by each KMP a. Fully Paid Ordinary Shares The number of ordinary shares of The Agency Group Australia Ltd held, directly, indirectly or beneficially, by each KMP, including their personally-related entities for the year ended 30 June 2026: 2026 – Group Balance at start of Received during Received during the year or the year as year on the exercise Other changes Balance at end of Group KMP appointment compensation of options during the year year or termination No. No. No. No. No. Andrew Jensen 2,903,492 – – – 2,903,492 Paul Niardone(1) 14,187,008 – – 140,000 14,327,008 Adam Davey 1,700,001 – – – 1,700,001 Michael Schaper 367,134 – – – 367,134 (2) Melissa Peters 134,000,000 – – – 134,000,000 Matthew Lahood 24,804,398 – – – 24,804,398
177,962,033 – – 140,000 178,102,033 (1) Mr Niardone’s other changes related to on-market purchases (2) Ms Peters was appointed on 1 May 2026. She is the managing director of Peters Investments Pty Ltd and therefore has relevant interest in those shares by nature of her position.
b. Options No options over ordinary shares in The Agency Group Australia Ltd were held, directly, indirectly, or beneficially, by any member of KMP, including their personally-related entities for the year ended 30 June 2026.
P a g e | 18
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Directors’ report
15. Remuneration report (audited)
c. Performance Shares / Rights No performance shares in The Agency Group Australia Ltd were held, directly, indirectly, or beneficially, by any member of KMP, including their personally-related entities for the year ended 30 June 2026.
15. Remuneration report (audited) 15.9. Other Equity-related KMP Transactions There have been no other transactions involving equity instruments other than those described in the tables above relating to options, rights, and shareholdings.
END OF REMUNERATION REPORT
This Report of the Directors, incorporating the Remuneration Report, is signed in accordance with a resolution of the Board of Directors made pursuant to section 298(2) of the Corporations Act 2001 (Cth).
ANDREW JENSEN Executive Chairman Dated this Monday, 31 August 2026
P a g e | 19
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Auditor’s independence declaration Under section 307C of the Corporations Act 2001 (Cth) To the Directors of THE AGENCY GROUP AUSTRALIA LTD
TO BE RECEIVED FROM AUDITORS
P a g e | 20
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Consolidated statement of profit or loss and other comprehensive income for the year ended 30 June 2026 Note 2026 2025 $’000 $’000 Continuing operations Revenue 1.1 108,726 98,541 Cost of sales (73,047) (66,478)
Gross profit 35,679 32,063
Other income 1.2 1,032 738
Administrative and other expenses (36,298) (35,592)
Profit / (loss) before tax and finance costs 413 (2,791)
Share of profit or (loss) from equity accounted investments 11.3.2 15 75 Interest and finance costs (1,943) (2,042) Embedded derivative non-cash financing (costs) or gains 2.2 (857) (679)
Loss before tax 2.1 (2,372) (5,437)
Income tax benefit 4.1 – –
Loss for the year (2,372) (5,437)
Other comprehensive income, net of income tax ◼ Items that will not be reclassified subsequently to profit or loss: – – ◼ Items that may be reclassified subsequently to profit or loss: – –
Other comprehensive income for the period, net of tax – –
Total comprehensive income attributable to members of the parent entity (2,372) (5,437)
Earnings per share: ₵ ₵ Basic (loss) / earnings per share (cents per share) 19.4 (0.54) (1.25) Diluted earnings per share (cents per share) 19.4 N/A N/A 4,861 3,758 The consolidated statement of profit or loss and other comprehensive income is to be read in conjunction with the accompanying notes.
P a g e | 21
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Consolidated statement of financial position as at 30 June 2026 Note 2026 2025 $’000 $’000 Current assets Cash and cash equivalents 5.1 4,243 5,065 Trade and other receivables 5.2.1 13,118 14,247 Other current assets 5.4.1 2,138 1,096
Total current assets 19,499 20,408
Non-current assets Trade and other receivables 5.2.2 1,065 420 Financial assets 5.3.1 1,194 1,001 Property, plant, and equipment 6.1 1,931 1,737 Right-of-use assets 6.2.1 6,524 7,700 Intangible assets 6.3 16,202 17,323 Investments accounted for using the equity method 11.1 289 350
Total non-current assets 27,205 28,531
Total assets 46,704 48,939
Current liabilities Trade and other payables 5.5.1 20,275 20,988 Borrowings 5.6.1 – 8,400 Financial liabilities 5.7.1 5,533 4,293 Provisions 6.4.1 4,260 3,453 Leases 6.2.2 2,397 2,440
Total current liabilities 32,465 39,574
Non-current liabilities Borrowings 5.6.2 8,400 – Provisions 6.4.2 394 402 Leases 6.2.2 5,364 6,510 Deferred tax liabilities 4.6 – –
Total non-current liabilities 14,158 6,912
Total liabilities 46,623 46,486
Net assets 81 2,453
Equity – – Issued capital 7.1.1 44,163 44,163 Reserves 7.4 50 50 Accumulated losses (44,132) (41,760)
Total equity 81 2,453 (12,966) (19,166) (16,121) (14,870) The consolidated statement of financial position is to be read in conjunction with the accompanying notes.
P a g e | 22
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Consolidated statement of changes in equity for the year ended 30 June 2026 Note Share-based Issued Accumulated payment Total capital losses reserve equity $’000 $’000 $’000 $’000
Balance at 1 July 2024 43,635 (36,682) 937 7,890 Loss for the year attributable to owners of the parent – (5,437) – (5,437) Other comprehensive income for the year attributable to owners of the parent – – – – Total comprehensive income for the year attributable to owners of the parent – (5,437) – (5,437)
Transaction with owners, directly in equity Conversion of performance rights 7.1,7.2 528 – (528) – Transfers to / from reserves 7.3 – 359 (359) –
Balance at 30 June 2025 44,163 (41,760) 50 2,453
Balance at 1 July 2025 44,163 (41,760) 50 2,453 Loss for the year attributable to owners of the parent – (2,372) – (2,372) Other comprehensive income for the year attributable to owners of the parent – – – –
Total comprehensive income for the year attributable to owners of the parent – (2,372) – (2,372)
Transaction with owners, directly in equity Conversion of performance rights – – – – Transfers to / from reserves on option expiry – – – –
Balance at 30 June 2026 44,163 (44,132) 50 81
The consolidated statement of changes in equity is to be read in conjunction with the accompanying notes.
P a g e | 23
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Consolidated statement of cash flows for the year ended 30 June 2026 Note 2026 2025 $’000 $’000 Cash flows from operating activities Receipts from customers 111,560 102,847 Payments to suppliers and employees (107,224) (97,852) Interest received 12 9 Finance costs (832) (818)
Net cash provided by operating activities 5.1.2a 3,516 4,186
Cash flows from investing activities Purchase of property, plant, and equipment (640) (633) Purchase of intangibles (579) (630) Purchase of investments (75) – (Deposit for) / release of bank guarantees (118) 18 Proceeds from disposal of shares via buyback 352 140 Proceeds from loans to other entities 203 –
Net cash (used in) / provided by investing activities (857) (1,105)
Cash flows from financing activities
Payment of principal portion of lease liabilities 5.1.2b (3,481) (2,920)
Net cash (used in) financing activities (3,481) (2,920)
Net (decrease) / increase in cash and cash equivalents held (822) 161 Cash and cash equivalents at the beginning of the year 5,065 4,904
Cash and cash equivalents at the end of the year – – 5.1 4,243 5,065
The consolidated statement of cash flows is to be read in conjunction with the accompanying notes.
P a g e | 24
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
In preparing the 2026 financial statements, The Agency Group Australia Ltd has grouped notes into sections under five key categories: ◼ Section A: How the numbers are calculated ……………………………………………………………………………………………………………..26
◼ Section B: Risk ………………………………………………………………………………………………………………………………………………………49
◼ Section C: Group structure ……………………………………………………………………………………………………………………………………..53
◼ Section D: Unrecognised items ……………………………………………………………………………………………………………………………….59
◼ Section E: Other Information ………………………………………………………………………………………………………………………………….60
Material accounting policies specific to each note are included within that note. Accounting policies that are determined to be non- material are not included in the financial statements. The financial report is presented in Australian dollars, except where otherwise stated. The amounts contained in these financial statements have been rounded to the nearest thousand dollars under the option available to the Group under Australian Securities and Investments Commission (ASIC) Corporations (Rounding in Financial/Directors’ Reports) Instrument 2016/191 dated 24 March 2016.
Company details The registered office and head office of the Company is: Street: 68 Milligan Street Postal: PO Box 7768 Perth WA 6000 CLOISTERS SQUARE WA 6850 Australia Australia
P a g e | 25
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
SECTION A. HOW THE NUMBERS ARE CALCULATED This section provides additional information about those individual line items in the financial statements that the Directors consider most relevant in the context of the operations of the entity, including: (a) accounting policies that are relevant for an understanding of the items recognised in the financial statements. These cover situations where the accounting standards either allow a choice or do not deal with a particular type of transaction. (b) analysis and sub-totals. (c) information about estimates and judgements made in relation to particular items.
Note 1 Revenue and other income 2026 2025 $’000 $’000
1.1 Revenue Residential sales commissions 92,118 82,790 Mortgage and settlement revenue 2,123 2,253 Property management revenue: Management fees 10,540 9,759 Other 3,945 3,739
108,726 98,541
1.2 Other income 2026 2025 $’000 $’000 Interest income 53 51 Gain on sale of property, plant, and equipment and on exit of lease 339 49 Agent desk fees 407 381 Other income 233 257
1,032 738 1.3 Accounting policies 1.3.1 Revenue from contracts with customers Revenue is measured based on the consideration specified in a contract with a customer. The Group recognises revenue when performance obligations have been met. Revenue is measured at the fair value of the consideration received or receivable. Amounts disclosed as revenue are net of returns, trade allowances and amounts collected on behalf of third parties. 1.3.2 Revenue is recognised for major business activities based on the following performance obligations: (a) Settlement fee revenue ……………………………………. on the settlement of real estate transaction. (b) Upfront commissions for mortgage origination …… on the approval of finance to clients and settlement of real estate transaction. (c) Trail commissions ……………………………………………… on the receipt, based on maintaining clientele. (d) Real estate commissions ……………………………………. when the sale of the property becomes unconditional. (e) Training seminars and functions ………………………… on date function is held. All revenue is stated net of the amounts of goods and services tax (GST).
1.3.3 Interest income Interest revenue is recognised in accordance with note 3.1 Finance income and expenses.
P a g e | 26
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 1 Revenue and other income (cont.)
1.3.4 Critical judgements – Recognition of trailing commission revenue & trailing commission expense The Group receives trailing commissions from lenders on loans they have settled that were originated by the Group. The trailing commissions are received over the life of the loans based on the individual loan balance outstanding. The Group also makes trailing commission payments to brokers based on the individual loan balance outstanding. As disclosed in note 1.3.2(c) above, revenue from trailing commission is recognised on receipt. The Directors considered the detailed criteria for the recognition of revenue from the rendering of services set out in AASB 15 Revenue from contracts with customers, in particular, whether the recognition of revenue on the trail satisfied the probability requirements. The Directors determined that at the contract level, the Group cannot reliably determine the likelihood of that individual remaining with the Group or the period that they will continue for, resulting in revenue only being recognised upon receipt. Trailing commission expenditure is recognised on the same basis as trailing commission revenue and is recognised upon receipt of trailing commission revenue.
Note 2 Expenses Note 2026 2025 $’000 $’000 2.1 Expenses by nature ◼ Advertising and promotion expenses 4,618 4,012 ◼ Computers and information technology expenses 3,070 2,729 ◼ Consultancy fees 1,318 1,105 ◼ Depreciation and amortisation 2.4 4,733 6,619 ◼ Embedded derivative non-cash financing costs 2.2 857 679 ◼ Interest and finance costs 1,943 2,042 ◼ Legal and professional fees 2,115 1,896 ◼ Occupancy costs 1,386 1,523 ◼ Salaries and employment costs 2.3 88,301 80,839 ◼ Share of associate’s profit or loss 11.3.2 (15) (75) ◼ Travel and entertainment 895 797 ◼ Other expense 2,909 2,550
Total expenses by nature 112,130 104,716
Reconciliation to net profit or loss before tax Total revenue and other income 109,758 99,279 Less: Total expenses by nature (112,130) (104,716)
Net loss before tax (2,372) (5,437) – –
Note 2026 2025 2.2 Convertible note non-cash financing (gains)/costs: $’000 $’000
◼ Convertible note – Finance cost 496 990 ◼ Embedded Derivative – Fair value adjustment 5.7.2 361 (311)
857 679
P a g e | 27
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 2 Expenses (cont.)
2.3 Salaries and employment costs 2026 2025 $’000 $’000 ◼ Commissions 57,284 53,505 ◼ Director fees 231 210 ◼ Salary and wages 16,715 15,128 ◼ Superannuation (on commissions, director fees, and salary and wages) 5,257 3,905 ◼ Payroll taxes 3,498 3,175 ◼ Other employment related costs 5,316 4,916
88,301 80,839 2.3.1 Accounting policy a. Short-term benefits Liabilities for employee benefits for wages, salaries and annual leave that are expected to be settled within 12 months of the reporting date represent present obligations resulting from employees’ services provided to the reporting date and are calculated at undiscounted amounts based on remuneration wage and salary rates that the Group expects to pay at the reporting date including related on-costs, such as workers compensation insurance and payroll tax. Non-accumulating non-monetary benefits, such as medical care, housing, cars and free or subsidised goods and services, are expensed based on the net marginal cost to the Group as the benefits are taken by the employees.
b. Other long-term benefits The Group’s obligation in respect of long-term employee benefits other than defined benefit plans, such as long service leave, is the amount of future benefit that employees have earned in return for their service in the current and prior periods plus related on-costs; that benefit is discounted to determine its present value, and the fair value of any related assets is deducted. The discount rate is the Reserve Bank of Australia’s cash rate at the report date that have maturity dates approximating the terms of the Company’s obligations. Any actuarial gains or losses are recognised in profit or loss in the period in which they arise.
c. Retirement benefit obligations: Defined contribution superannuation funds A defined contribution plan is a post-employment benefit plan under which an entity pays fixed contributions on to a separate entity and will have no legal or constructive obligation to pay further amounts. Obligations for contributions to defined contribution superannuation funds are recognised as an expense in the income statement as incurred.
d. Termination benefits When applicable, the Group recognises a liability and expense for termination benefits at the earlier of: (a) the date when the Group can no longer withdraw the offer for termination benefits; and (b) when the Group recognises costs for restructuring pursuant to AASB 137 Provisions, Contingent Liabilities and Contingent Assets and the costs include termination benefits. In either case, unless the number of employees affected is known, the obligation for termination benefits is measured based on the number of employees expected to be affected. Termination benefits that are expected to be settled wholly before 12 months after the annual reporting period in which the benefits are recognised are measured at the (undiscounted) amounts expected to be paid. All other termination benefits are accounted for on the same basis as other long-term employee benefits.
e. Equity-settled compensation The fair value of options granted is recognised as an employee expense with a corresponding increase in equity. The fair value is measured at grant date and spread over the period during which the employees become unconditionally entitled to the options. The fair value of the options granted is measured using the Black-Scholes pricing model, considering the terms and conditions upon which the options were granted. The amount recognised is adjusted to reflect the actual number of share options that vest except where forfeiture is only due to market conditions not being met.
P a g e | 28
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 2 Expenses (cont.) 2.4 Depreciation and amortisation Note 2026 2025 $’000 $’000 ◼ Depreciation – plant and equipment 6.1.1 446 395 ◼ Depreciation – right-of-use assets 6.2.4 2,588 2,135 ◼ Amortisation – intangible assets 6.3.1 1,699 4,089
4,733 6,619
Note 3 Other material accounting policies related to items of profit and loss 3.1 Finance income and expenses Finance income comprises interest income on funds invested, gains on the disposal of available-for-sale financial assets and changes in the fair value of financial assets at fair value through profit or loss. Interest revenue is recognised on a time proportionate basis that considers the effective yield on the financial asset. Financial expenses comprise interest expense on borrowings calculated using the effective interest method, unwinding of discounts on provisions, changes in the fair value of financial assets at fair value through profit or loss and impairment losses recognised on financial assets. All borrowing costs are recognised in profit or loss using the effective interest method. Borrowing costs directly attributable to the acquisition, construction or production of assets that necessarily take a substantial period of time to prepare for their intended use or sale, are added to the cost of those assets, until such time as the assets are substantially ready for their intended use or sale. All other borrowing costs are recognised in income in the period in which they are incurred.
Note 4 Income tax Note 2026 2025 $’000 $’000 4.1 Income tax benefit Current tax expense – – Deferred tax expense – –
– –
Deferred income tax expense included in income tax expense comprises: ◼ (Increase) / decrease in deferred tax assets (DTAs) 4.5 407 979 ◼ Increase / (decrease) in deferred tax liabilities (DTLs) 4.6 (407) (979)
– – 4.2 Reconciliation of income tax expense to prima facie tax payable The prima facie tax benefit on profit or loss from ordinary activities before income tax is reconciled to the income tax expense as follows: Accounting profit / (loss) before tax (2,372) (5,437)
Prima facie tax on operating loss at 30% (2025 loss: 30%) (712) (1,631) Add / (less) tax effect of: ◼ Non-deductible expenses 531 260 ◼ Unrecognised income tax benefit in respect of current year losses and 181 1,371 timing differences
Income tax benefit attributable to operating profit or (loss) – –
P a g e | 29
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 4 Income tax (cont.) 2026 2025 % % 4.3 The applicable weighted average effective tax rates attributable to operating profit are as follows: – – a. The tax rates used in the above reconciliations are the corporate tax rate of 30% payable by the Australian corporate entity on taxable profits under Australian tax law.
4.4 Balance of franking account at year end of the parent company $nil $nil
4.5 Deferred tax assets (DTA) Note 2026 2025 $’000 $’000 Employee benefits 1,241 1,252 Accrued expenses 149 207 Provisions 450 401 AASB 16 Leases – Lease liability 371 375 Tax losses 1,576 5,481 Other 75 74 3,862 7,790
Set-off deferred tax liabilities 4.6 (889) (1,296) Net deferred tax assets 2,973 6,494 Less: deferred tax assets not recognised (2,973) (6,494)
Net deferred tax assets – –
4.6 Deferred tax liabilities (DTL) Intangible asset – rent rolls 802 1,198 Financial assets – investments (fair valuation) 87 98 889 1,296
Set-off deferred tax assets 4.5 (889) (1,296)
Net deferred tax liabilities – –
4.7 Tax losses and deductible temporary differences Unused tax losses and deductible temporary differences for which no DTA has been recognised, that may be utilised to offset tax liabilities: ◼ Revenue losses attributable to Australia 1,576 5,481
1,576 5,481
4.8 Potential deferred tax assets attributable to tax losses have not been brought to account at 30 June 2026 because the Directors do not believe it is appropriate to regard realisation of the deferred tax assets as probable at this point in time. These benefits will only be obtained if: i. the Group derives future assessable income of a nature and of an amount sufficient to enable the benefit from the deductions for the loss to be realised; ii. the Company continues to comply with conditions for deductibility imposed by law; and iii. no changes in tax legislation adversely affect the Group in realising the benefit from the deductions for the loss. Balances disclosed in the financial statements and the notes thereto, related to taxation, are based on the best estimates of the Directors. These estimates consider both the financial performance and position of the Company as they pertain to current income taxation legislation, and the Directors’ understanding thereof. No adjustment has been made for pending or future taxation legislation. The current income tax position represents the Directors’ best estimate, pending an assessment by tax authorities in relevant jurisdictions.
P a g e | 30
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 4 Income tax (cont.) Note
The parent company has accumulated tax losses of $16,901K (2025: $18,271K). These include $5,252K of Group losses and $11,649K of transferred losses from historical acquisitions which require further testing to be undertaken to confirm their future availability (previous testing indicated the best available fraction to apply to these losses was no higher than 8.4%). Management has taken a prudent approach this year and only disclosed an unrecognised DTA for group losses totalling $5,252K, which are expected to be available under the relevant tax loss recoupment rules.
4.9 Accounting policy The income tax expense or benefit for the period is the tax payable on the current period’s taxable income based on the applicable income tax rate for each jurisdiction adjusted by changes in deferred tax assets and liabilities attributable to temporary difference and to unused tax losses. The current income tax charge is calculated based on the Australian tax laws enacted or substantively enacted at the end of the reporting period being where the Group and its associates operate and generate taxable income. Management periodically evaluates positions taken in tax returns with respect to situations in which applicable tax regulation is subject to interpretation. It establishes provisions where appropriate based on amounts expected to be paid to the tax authorities. Current tax assets and liabilities for the current and prior periods are measured at the amount expected to be recovered from or paid to the taxation authorities. The tax rates and tax laws used to compute the amount are those that are enacted or substantively enacted by the balance date, in Australia. Deferred income tax is provided on all temporary differences at the balance date between the tax bases of assets and liabilities and their carrying amounts for financial reporting purposes. Deferred income tax liabilities (DTL) are recognised for all taxable temporary differences except: ◼ when the DTL arises from the initial recognition of goodwill or of an asset or liability in a transaction that is not a business combination and that, at the time of the transaction, affects neither the accounting profit nor taxable profit or loss; or ◼ when the taxable temporary difference is associated with investments in subsidiaries, associates or interests in joint ventures, and the timing of the reversal of the temporary difference can be controlled and it is probable that the temporary difference will not reverse in the foreseeable future. Deferred income tax assets (DTA) are recognised for all deductible temporary differences, carry-forward of unused tax assets and unused tax losses, to the extent that it is probable that taxable profit will be available against which the deductible temporary differences and the carry-forward of unused tax credits and unused tax losses can be utilised, except: ◼ when the DTA relating to the deductible temporary difference arises from the initial recognition of an asset or liability in a transaction that is not a business combination and, at the time of the transaction, affects neither the accounting profit nor taxable profit or loss; or ◼ when the deductible temporary difference is associated with investments in subsidiaries, associates or interests in joint ventures, in which case a DTA is only recognised to the extent that it is probable that temporary differences will reverse in the foreseeable future and taxable profit will be available against which the temporary difference can be utilised. The carrying amount of DTA is reviewed at each balance date and reduced to the extent that it is no longer probable that sufficient taxable profit will be available to allow all or part of the DTA to be utilised. Unrecognised DTA are reassessed at each balance date and are recognised to the extent that it has become probable that future taxable profit will allow the deferred tax asset to be recovered. DTAs and DTLs are measured at the tax rates that are expected to apply to the year when the asset is realised or the liability is settled, based on tax rates (and tax laws) that have been enacted or substantively enacted at the balance date. Income taxes relating to items recognised directly in equity are recognised in equity and not in profit or loss. DTAs and DTLs are offset only if a legally enforceable right exists to set off current tax assets against current tax liabilities and the DTAs and DTLs relate to the same taxable entity and the same taxation authority.
4.9.1 Tax consolidation The Agency Group Australia Ltd and its wholly-owned Australian subsidiaries have formed an income tax consolidated group (the Tax Group) under the tax consolidation legislation. Each entity in the Tax Group recognises its own current and deferred tax liabilities, except for any DTLs resulting from unused tax losses and tax credits, which are immediately assumed by the parent entity. The Group notified the Australian Tax Office that it had formed a Tax Group to apply from 1 July 2019. The Tax Group has entered a tax sharing agreement whereby each company in the Tax Group contributes to the income tax payable in proportion to their contribution to the net profit before tax of the Tax Group.
P a g e | 31
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 5 Financial assets and financial liabilities
5.1 Cash and cash equivalents 2026 2025 $’000 $’000 Cash at bank 4,243 5,065
4,243 5,065
5.1.1 The Group’s exposure to interest rate risk and a sensitivity analysis for financial assets and liabilities are disclosed in note 8 Financial risk management.
Note 2026 2025 5.1.2 Cash Flow Information $’000 $’000 a. Reconciliation of cash flow from operations to loss after income tax Loss after income tax (2,372) (5,437) ◼ Cash flows excluded from loss attributable to operating activities Business acquisition costs (107) – ◼ Non-cash flows in loss from ordinary activities: Depreciation and amortisation 2.4 4,733 6,619 Non-cash interest adjustments 1,069 987 Convertible note non-cash financing costs 2.2 857 679 Profit or loss on disposal of assets (339) (49) Share of profit or (loss) from equity accounted investments 11.3.2 (15) (75) ◼ Changes in assets and liabilities, net of the effects of purchase and disposal of subsidiaries: (Increase) or decrease in receivables(I) 97 (328) (Increase) or decrease in financial assets 118 (18) Increase or (decrease) in trade and other payables(I) (1,324) 1,539 Increase or (decrease) in provisions 799 269
Cash flow from operations – 3,516 4,186 – –
b. Reconciliation of liabilities arising from financing activities Non-cash changes Other Embedded Converted 2024 Cash flows Additions changes derivative to equity 2025 $’000 $’000 $’000 $’000 $’000 $’000 $’000
Short-term borrowings 3,258 – – 9,745 (310) – 12,693 and financial liabilities Long-term borrowings 8,400 – – (8,400) – – – and financial liabilities Leases 4,412 (2,920) 6,773 685 – – 8,950 Total liabilities from financing activities 16,070 (2,920) 6,773 2,030 (310) – 21,643 –
(I) Items within the trade and other receivables and trade and other payables have been reclassified between line items to better reflect their nature, and comparative figures have been reclassified accordingly; these changes had no impact on net profit, earnings per share or net assets.
P a g e | 32
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 5 Financial assets and financial liabilities (cont.)
5.1 Cash and cash equivalents (cont.) 5.1.2 Cash Flow Information (cont.) Non-cash changes Other Embedded Converted 2025 Cash flows Additions changes derivative to equity 2026 $’000 $’000 $’000 $’000 $’000 $’000 $’000 Short-term borrowings 12,693 – – (7,521) 361 – 5,533 and financial liabilities Long-term borrowings – – – 8,400 – – 8,400 and financial liabilities Leases 8,950 (3,481) 1,572 720 – – 7,761 Total liabilities from financing activities 21,643 (3,481) 1,572 1,599 361 – 21,694 – –
c. Credit and loan standby arrangement with banks Refer note 5.6.5 Financing facilities available.
d. Non-cash investing and financing activities 2026 ◼ Reclassification of borrowings to non-current. 2025 ◼ Reclassification of borrowings to current.
5.1.3 Accounting policy For Statement of Cash Flow presentation purposes, cash and cash equivalents includes cash on hand, deposits held at call with financial institutions, other short-term, highly liquid instruments with original maturities of three months or less that are readily convertible to known amounts of cash and which are subject to an insignificant risk of changes in value, and bank overdrafts. Bank overdrafts are shown within borrowings in current liabilities on the Statement of Financial Position.
5.2 Trade and other receivables Note 2026 2025 $’000 $’000 5.2.1 Current Trade debtors 11,010 11,402 Recoverable commissions and wages(II) 1,095 1,138 Other receivables 1,117 1,756 Provision for non-recovery of trade debtors and commissions / wages (460) (608) Loan to KMP 5.2.1a 356 559
13,118 14,247
a. As at 30 June 2026, an amount of $355,701 was advanced to Mr Lahood (2025: $559,291), refer also note 18.1a.
2026 2025 5.2.2 Non-current $’000 $’000 Trade debtors 1,065 420
1,065 420
5.2.3 The Group’s exposure to credit risk is disclosed in note 8 Financial risk management.
(II) Items within the trade and other receivables and trade and other payables have been reclassified between line items to better reflect their nature, and comparative figures have been reclassified accordingly; these changes had no impact on net profit, earnings per share or net assets.
P a g e | 33
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 5 Financial assets and financial liabilities (cont.)
5.2 Trade and other receivables (cont.) 5.2.4 The average credit period on rendering of services ranges from current to 30 days. Interest is not charged. An allowance has been made for estimated irrecoverable trade receivable amounts arising from past sale of goods and rendering of services, determined by reference to past default experience. Amounts are considered as past due when the debt has not been settled, within the terms and conditions agreed between the Group and the customer or counter party to the transaction.
5.2.5 Accounting policy Trade receivables are recognised initially at fair value and subsequently measured at amortised cost, less provision for doubtful debts. Trade receivables are due for settlement within 30 days. Marketing allowances and upfront commissions paid to employees and agents are recovered against future sales commissions received by the employee or agent.
a. Determining the stage for impairment At each reporting date, the Group assesses whether there has been a significant increase in credit risk for exposures since initial recognition by comparing the risk of default occurring over the remaining expected life from the reporting date and the date of initial recognition. The Group considers reasonable and supportable information that is relevant and available without undue cost or effort for this purpose. This includes quantitative and qualitative information and also, forward-looking analysis. An exposure will migrate through the expected credit loss (ECL) stages as asset quality deteriorates. If, in a subsequent period, asset quality improves and also reverses any previously assessed significant increase in credit risk since origination, then the provision for doubtful debts reverts from lifetime ECL to 12-month’s ECL. Exposures that have not deteriorated significantly since origination are considered to have a low credit risk. The provision for doubtful debts for these financial assets is based on 12-month’s ECL. When an asset is uncollectible, it is written off against the related provision. Such assets are written off after all the necessary procedures have been completed and the amount of the loss has been determined. Subsequent recoveries of amounts previously written off reduce the amount of the expense in the Consolidated Statement of Profit or Loss and Other Comprehensive Income. The Group assesses whether the credit risk on an exposure has increased significantly on an individual or collective basis. For the purposes of a collective evaluation of impairment, financial instruments are grouped on the basis of shared credit risk characteristics, taking into account instrument type, credit risk ratings, date of initial recognition, remaining term to maturity, industry, geographical location of the borrower and other relevant factors.
5.3 Financial assets Note 2026 2025 $’000 $’000 5.3.1 Non-current Bank guarantees and rental bonds 1,119 1,001 Financial assets at FVPL 5.3.2 75 –
1,194 1,001 5.3.2 Accounting policy a. Recognition and Measurement The Group classifies the equity investments for which the entity has not elected to recognise fair value gains and losses through OCI as financial assets at fair value through profit or loss (FVPL)(refer to note 5.8.1c).
5.4 Other assets 2026 2025 $’000 $’000 5.4.1 Current Prepayments 2,080 1,048 Other deposits 58 48
2,138 1,096
P a g e | 34
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 5 Financial assets and financial liabilities (cont.)
5.5 Trade and other payables 2026 2025 $’000 $’000 5.5.1 Current Trade payables 4,487 2,697 VPA creditors(III) 1,343 688 Employees’ remuneration – commissions payable 6,670 7,670 Payroll tax 349 311 Superannuation – employees 415 368 Sundry creditors and accrued expenses 3,801 4,512 GST and PAYG payable 3,210 4,742
20,275 20,988 5.5.2 Trade payables are unsecured, non-interest-bearing and are normally settled on 30-day terms. Other payables are unsecured non-trade payables, non-interest-bearing, and have an average term of 1 month. 5.5.3 Accounting policy a. Trade and other payables These amounts represent liabilities for goods and services provided to the Group prior to the end of the financial year which are unpaid. The amounts are unsecured and are usually paid within 30 days of recognition. Trade and other payables are presented as current liabilities unless payment is not due within 12 months.
5.6 Borrowings Note 2026 2025 $’000 $’000 5.6.1 Current Bank loans 5.6.3 – 8,400
– 8,400 5.6.2 Non-current Bank loans 5.6.3 8,400 –
8,400 – 5.6.3 Debt facility In July 2025, the Company entered into an Amendment Deed with Macquarie Bank Limited on the following revised terms: ◼ Reduction in the interest rate margin from 3.75% to 3.25%; ◼ Extension of the facility maturity to 30 June 2028; ◼ Addition of a $1.6 million draw down facility to fund growth initiatives; ◼ Removal of the interest cover ratio covenant; and ◼ Introduction of a new minimum liquidity covenant requiring aggregate cash holdings (excluding amounts under the asset growth fund) of greater than $1.45 million, increasing to $2.0 million from 1 July 2026.
5.6.4 Assets pledged as security Security is held over all the Group companies.
5.6.5 Financing facilities available At balance date, the following Total facilities Facilities used Facilities unused financing facilities had been 2026 2025 2026 2025 2026 2025 negotiated and were available: $’000 $’000 $’000 $’000 $’000 $’000 Bank and other loans 10,000 8,400 (8,400) (8,400) 1,600 –
Total facilities at balance date 10,000 8,400 (8,400) (8,400) 1,600 –
(III) Items within the trade and other receivables and trade and other payables have been reclassified between line items to better reflect their nature, and comparative figures have been reclassified accordingly; these changes had no impact on net profit, earnings per share or net assets.
P a g e | 35
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 5 Financial assets and financial liabilities (cont.)
5.6 Borrowings (cont.) 5.6.6 Accounting policy a. Borrowings Borrowings are initially recognised at fair value, net of transaction costs. They are subsequently measured at amortised cost, with any difference between the proceeds (net of transaction costs) and the redemption amount recognised in profit or loss over the term of the borrowings using the effective interest method. Fees on the establishment of loan facilities are recognised as transaction costs when it is probable that the facility will be drawn. In this case, the fee is deferred until drawdown. Where it is not probable that the facility will be drawn, the fee is capitalised as a prepayment for liquidity services and amortised over the facility period. Borrowings are removed from the statement of financial position when the contractual obligation is discharged, cancelled, or expired. The difference between the carrying amount of the liability extinguished or transferred and the consideration paid, including non-cash assets transferred or liabilities assumed, is recognised in profit or loss as other income or finance costs. Borrowings are classified as current liabilities unless the Group has an unconditional right to defer settlement for at least 12 months after the reporting period.
5.7 Financial liabilities Note 2026 2025 $’000 $’000 5.7.1 Current Convertible note: 5.7.2,5.7.3 ◼ Debt component 3,805 3,827 ◼ Derivative financial liability conversion option 1,728 466
5,533 4,293 5.7.2 Reconciliation of convertible notes Opening balance: ◼ Debt component 3,827 2,481 ◼ Derivative financial liability conversion option 466 777 4,293 3,258 ◼ Interest charged 879 1,346 ◼ Fair value movement: Fair value changes 361 (311)
Carrying value of liabilities at reporting date 5,533 4,293
5.7.3 On 5 January 2021, the Company issued 5,000,000 convertible notes to Peters Investments Pty Ltd (the Noteholder) to raise $5,000,000. On 28 January 2021, of the 5,000,000 notes, Peters Investments converted $2,056,634 of debt and interest into 76,171,620 shares. The details of the convertible note are as follows: ◼ Interest rate higher of 8% per annum and the interest rate on the Macquarie Bank Limited (MBL) loan ◼ Facilitation fee 3% fee equalling $150,000 which is capitalised and added to the face value of the note. ◼ Security Second security ranking behind MBL. ◼ Options 12,000,000 Options (exercised at $0.027 on 28 January 2021). ◼ Term/Maturity date On 22 July 2022 (and approved at the Company’s AGM on 18 November 2022), the Company signed a Deed of Variation to Convertible Note Agreement, to extend the terms of the convertible note to 22 January 2026. Unless converted to shares, the notes will be repaid in cash on the earlier of 22 January 2026 or when all amounts owing by the Company to MBL have been repaid. ◼ Conversion At the Noteholder’s election the notes can be converted into shares in the Company at the lower of $0.027 per share and the issue price of shares offered under any subsequent capital raising completed by the Company to raise over $1,000,000 on or before maturity date. ◼ Other conditions The Noteholder will have the first right of refusal to replace the MBL loan on commercial terms and conditions to be reasonably agreed between the Noteholder and The Agency. The note holder is a related party as detailed in note 18.2 Related party financial liabilities.
P a g e | 36
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 5 Financial assets and financial liabilities (cont.)
5.7 Financial liabilities (cont.) On 21 July 2025, the Company announced that it executed a further Deed of Variation with Peters Investments Pty Ltd to the convertible note agreement, which was approved by shareholders on 27 August 2025. The amendment changes the maturity date of the Convertible Notes from 22 January 2026 to 31 December 2028, aligning with the extended maturity of the Company’s secured debt facility. With the extension of the convertible note from 22 January 2026 to 31 December 2028 agreed at the Company general meeting on 27 August 2025, this resulted in a substantial modification of the existing convertible note. The existing embedded derivative was derecognised. A new embedded derivative liability was recognised at its fair value and included as a transaction cost of the deemed new convertible loan, which will be amortised over the new terms of the note.
5.7.4 Accounting policies and critical estimates – Convertible notes a. Debt component The conversion feature of convertible notes (notes) is required to be separated from the notes and is accounted for separately as a derivative financial liability. As a result, the notes are initially recognised at a discounted amount. The discount is amortised as interest expense using the effective interest method over the terms of the notes. b. Classification of current – non-current Amendments to AASB 101 Presentation of Financial Statements, concerning the current–non-current classification of liabilities, considers the issuance of equity instruments to extinguish a liability as a settlement of that debt. As such, the terms of the conversion feature of the Company’s facility have led to the reclassification of the financial liabilities to current. c. Embedded derivative – Conversion feature The conversion feature in the notes represents the embedded derivative financial instrument in the host debt contract. The conversion feature represents the Group’s obligation to issue Company shares at a fixed price should noteholders exercise their conversion option. The embedded derivatives are carried in the Statement of Financial Position at their estimated fair value taking market participant assumptions into consideration, with any changes in fair value recognised in the Statement of Profit or Loss and Other Comprehensive Income. These values were calculated using the Black-Scholes option pricing model, applying the following inputs: Grant date Balance date Face value: $5,150,000 $5,000,871 Share price: $0.035 $0.026 Conversion price: $0.027 $0.027 Expiry date 31 March 2023 31 December 2028 Expected share price volatility: 100.0% 89.0% Risk-free interest rate: 1.90% 4.40% Value per conversion right $0.0219 $0.0139
d. Settlement of Convertible Notes Where notes are settled by issue of shares, the related financial liabilities are derecognised at their carrying value with the corresponding increase to share capital. Any costs incurred are recognised in profit or loss. Where notes are settled by payment of cash, the related financial liabilities are derecognised at their carrying value and the difference between total cash consideration paid and the carrying value of the financial liabilities derecognised is recognised in profit or loss.
e. Capitalised transaction costs The Company incurred transaction costs upon the issuance of the notes. Transaction costs relating to the notes have been allocated between the debt component and the conversion derivatives using the relating proportions of these on initial measurement of the instruments. Costs attributed to the debt component are amortised to finance expense over the term of the notes using the effective interest method. Costs allocated to the conversion derivatives are immediately recognised in the Statement of Profit or Loss and Other Comprehensive Income.
P a g e | 37
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 5 Financial assets and financial liabilities (cont.)
5.8 Other material accounting policies related to financial assets and liabilities 5.8.1 Investments and other financial assets a. Classification The Group classifies its financial assets in the following measurement categories: ◼ those to be measured subsequently at fair value (either through OCI or through profit or loss), and ◼ those to be measured at amortised cost. Classification depends on the entity’s business model for managing financial assets and contractual terms of cash flows. For assets measured at fair value, gains and losses will either be recorded in profit or loss or OCI. For investments in equity instruments that are not held for trading, this will depend on whether the group has made an irrevocable election at the time of initial recognition to account for the equity investment at fair value through other comprehensive income (FVOCI). The Group reclassifies debt investments when and only when its business model for managing those assets changes. b. Recognition and derecognition Regular way purchases and sales of financial assets are recognised on the trade date, when the Group commits to the transaction. Financial assets are derecognised when rights to cash flows expire or are transferred, and substantially all risks and rewards of ownership are passed on. c. Measurement At initial recognition, the Group measures financial assets at fair value plus, for assets not at fair value through profit and loss (FVPL), transaction costs directly attributable to acquisition. Transaction costs of FVPL assets are expensed in profit or loss. Financial assets with embedded derivatives are assessed in their entirety to determine whether cash flows represent solely payments of principal and interest. i. Debt instruments Subsequent measurement of debt instruments depends on the Group’s business model for managing the asset and the cash flow characteristics of the asset. Debt instruments are classified into three measurement categories: ◼ Amortised cost: Assets that are held for collection of contractual cash flows where those cash flows represent solely payments of principal and interest are measured at amortised cost. Interest income from these financial assets is included in finance income using the effective interest rate method. Any gain or loss arising on derecognition is recognised directly in profit or loss and presented in other gains/(losses). Impairment losses are presented as separate line item in the statement of profit or loss. ◼ FVOCI: Financial assets held both to collect contractual cash flows and for sale, where cash flows comprise solely principal and interest, are measured at FVOCI. Changes in carrying amounts are recognised in OCI, except for impairment gains or losses, interest income, and foreign exchange differences, which are recognised in profit or loss. On derecognition, cumulative gains or losses previously recognised in OCI are reclassified from equity to profit or loss within other gains/(losses). Interest income is recognised in finance income using the effective interest method. Foreign exchange differences are presented in other gains/(losses), and impairment expenses are shown separately in the statement of profit or loss. ◼ FVPL: Assets that do not meet the criteria for amortised cost or FVOCI are measured at FVPL. A gain or loss on a debt investment that is subsequently measured at FVPL is recognised in profit or loss and presented net within other gains/(losses) in the period in which it arises. ii. Equity instruments The Group measures all equity investments at fair value. Where management elects to present fair value gains and losses in OCI, they are not reclassified to profit or loss on derecognition. Dividends from such investments are recognised in profit or loss as other income when the right to receive payment is established. Changes in the fair value of financial assets at FVPL are recognised in other gains/(losses) in the statement of profit or loss as applicable. Impairment losses (and reversal of impairment losses) on equity investments measured at FVOCI are not reported separately from other changes in fair value. d. Impairment The Group assesses expected credit losses on debt instruments carried at amortised cost and FVOCI using a forward- looking approach. The methodology depends on whether there has been a significant increase in credit risk. For trade receivables, the Group applies the simplified approach under AASB 9, recognising lifetime expected losses from initial recognition.
P a g e | 38
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 6 Non-financial assets and financial liabilities
6.1 Property, plant, and equipment 2026 2025 $’000 $’000
Plant and equipment – at cost 3,045 2,675 Accumulated depreciation (2,149) (1,916)
896 759
Leasehold improvements – at cost 5,233 4,963 Accumulated amortisation (4,198) (3,985)
1,035 978
Total plant and equipment 1,931 1,737
6.1.1 Movements in carrying amounts Note Plant and Leasehold equipment improvements Total 5 $’000 $’000 $’000
Carrying amount at 1 July 2024 686 813 1,499 Additions 309 347 656 Disposals / write-offs (23) – (23) Depreciation expense (213) (182) (395)
Carrying amount at 30 June 2025 759 978 1,737 – – –
Carrying amount at 1 July 2025 759 978 1,737 Additions 370 270 640 Disposals / write-offs – – – Depreciation expense (233) (213) (446)
Carrying amount at 30 June 2026 896 1,035 1,931 – – –
P a g e | 39
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 6 Non-financial assets and financial liabilities (cont.)
6.1 Property, plant, and equipment (cont.) 6.1.2 Accounting policy a. Recognition and measurement Items of plant and equipment are measured on the cost basis and carried at cost less accumulated depreciation (see below) and impairment losses (see accounting policy 6.5.1 Impairment of non-financial assets). Cost includes expenditure that is directly attributable to the acquisition of the asset. The cost of self-constructed assets includes the cost of materials and direct labour, any other costs directly attributable to bringing the asset to a working condition for its intended use, and the costs of dismantling and removing the items and restoring the site on which they are located, and an appropriate proportion of production overheads. Cost includes the cost of replacing parts that are eligible for capitalisation when the cost of replacing the parts is incurred. Similarly, when each major inspection is performed, its cost is recognised in the carrying amount of the plant and equipment as a replacement only if it is eligible for capitalisation. Where considered material, the carrying amount of property, plant, and equipment is reviewed annually by Directors to ensure it is not in excess of the recoverable amount from these assets. The recoverable amount is assessed on the basis of the expected net cash flows that will be received from the asset’s employment and subsequent disposal. The expected net cash flows have not been discounted to their present values in determining recoverable amounts. Where parts of an item of property, plant, and equipment have different useful lives, they are accounted for as separate items of plant and equipment.
b. Subsequent costs The cost of replacing part of an item of plant and equipment is recognised in the carrying amount of the item if it is probable that the future economic benefits embodied within the part will flow to the Group and its cost can be measured reliably. Any costs of the day-to-day servicing of plant and equipment are recognised in the income statement as an expense as incurred.
c. Depreciation The depreciable amount of all fixed assets including building and capitalised lease assets, but excluding freehold land, is depreciated on either a straight-line basis or diminishing balance basis, whichever is considered most appropriate, over their useful lives to the Group commencing from the time the asset is held ready for use. Leasehold improvements are amortised over the remaining term of the lease. Depreciation rates and methods are reviewed annually for appropriateness. The depreciation rates used for the current and comparative period are:
Class 2026 2025 % % ◼ Leasehold improvements Over term of lease Over term of lease ◼ Plant and equipment: Office furniture and fittings 10 10 Office equipment 25 25 Motor vehicle 25 25 The carrying amount of plant and equipment is reviewed annually by Directors to ensure it is not in excess of the recoverable amount from these assets. The recoverable amount is assessed on the basis of the expected net cash flows which will be received from the assets’ employment and subsequent disposal. The expected net cash flows have not been discounted to their present values in determining recoverable amounts.
d. Derecognition and disposal An item of property, plant and equipment is derecognised upon disposal or when no further future economic benefits are expected from its use or disposal. The gain or loss on disposal of an item of property, plant and equipment is determined by comparing the proceeds from disposal with the carrying amount of the property, plant and equipment and is recognised net within other income in profit or loss. When revalued assets are sold, any related amount included in the revaluation reserve is transferred to retained earnings.
P a g e | 40
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 6 Non-financial assets and financial liabilities (cont.)
6.2 Leases 2026 2025 $’000 $’000 6.2.1 Right-of-use assets Properties 5,728 6,680 Printing equipment 796 1,020
6,524 7,700 6.2.2 Lease liabilities Current 2,397 2,440 Non-current 5,364 6,510
7,761 8,950
6.2.3 Additions to the right-of-use assets 996 6,962 a. The Group disposed of $102K in leases during the period. No profit or loss was recognised on disposal.
6.2.4 Amounts recognised in the statement of profit or loss: ◼ Depreciation charge of right-of-use assets: Properties 2,349 1,880 Printing equipment 239 255
2,588 2,135
◼ Interest expense (included in finance costs) 720 685
6.2.5 Total cash outflow for leases 3,481 2,920
6.2.6 Accounting policy a. Recognition and measurement Leases are recognised as a right-of-use asset and a corresponding liability at the date at which the leased asset is available for use by the Group.
i. Right-of-use assets The Group recognises a right of use asset at the commencement date of the lease. The right of use asset is initially measured at cost. The cost of right of use assets includes the amount of lease liabilities recognised, adjusted for any lease payments made at or before the commencement date, plus initial direct costs incurred and an estimate of costs to dismantle, remove or restore the leased asset, less any lease incentives received. Right-of-use assets are measured at cost comprising the following: ◼ the amount of the initial measurement of lease liability ◼ any lease payments made at or before the commencement date less any lease incentives received ◼ any initial direct costs, and ◼ restoration costs. Subsequent to initial measurement, the right of use asset is depreciated on a straight-line basis over the shorter of the lease term and the estimated useful life as follows: ◼ Properties 24 – 60 months ◼ Printing equipment 36 – 60 months Right of use assets are subject to impairment and are adjusted for any remeasurement of lease liabilities.
P a g e | 41
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 6 Non-financial assets and financial liabilities (cont.)
6.2 Leases (cont.) ii. Lease liabilities At the commencement date of the lease, the Group recognises lease liabilities at the present value of lease payment to be made over the lease term. The lease payments include fixed payments (including in substance fixed payments) less any lease incentives receivable, variable lease payments that depend on an index or a rate, and amounts expected to be paid under residual value guarantees. The lease payments also include the exercise price of a purchase option reasonably certain to be exercised by the Group and payments of penalties for terminating a lease, if the assessment of lease term reflects the Group exercising the option to terminate. The variable lease payments that do not depend on an index or a rate are recognised as expense in the period on which the event or condition that triggers the payments occurs. The present value of lease payments is discounted using the interest rate implicit in the lease or, if the rate cannot be readily determined, the Group’s incremental borrowing rate. The lease liability is measured at amortised cost using the effective interest method. After the commencement date, the amount of lease liabilities is increased to reflect the accretion of interest and reduced for the lease payments made. The amount of lease liability is remeasured when there is a change in future lease payments arising from a change in an index or rate, if there is a change in the Group’s estimate of the amount expected to be payable under a residual value guarantee, or if the Group changes its assessment of whether it will exercise a purchase, extension, or termination option. When the lease liability is remeasured, a corresponding adjustment is made to the carrying amount of the right of use asset, or is recognised in profit or loss if the carrying amount of the right of use asset has been reduced to zero. The Group has elected not to recognise right of use assets and lease liabilities for short term leases that have a lease term of 12 months or less and do not contain a purchase option, and leases of low value assets. The Group recognises the lease payments associated with these leases as an expense on a straight-line basis over the lease term.
b. Extension and termination options Extension options are included in the property leases of the Group. 6.2.7 Critical judgements in determining the lease term In determining the lease term, management considers all facts and circumstances that create an economic incentive to exercise an extension option, or not exercise a termination option. Extension options (or periods after termination options) are only included in the lease term if the lease is reasonably certain to be extended (or not terminated). For leases of properties and printing equipment, the following factors are normally the most relevant: ◼ If there are significant penalties to terminate (or not extend), the Group is typically reasonably certain to extend (or not terminate). ◼ If any leasehold improvements are expected to have a significant remaining value, the Group is typically reasonably certain to extend (or not terminate). ◼ Otherwise, the Group considers other factors including historical lease durations and the costs and business disruption required to replace the leased asset. The lease term is reassessed if an option is actually exercised (or not exercised) or the Group becomes obliged to exercise (or not exercise) it. The assessment of reasonable certainty is only revised if a significant event or a significant change in circumstances occurs, which affects this assessment, and that is within the control of the lessee.
P a g e | 42
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 6 Non-financial assets and financial liabilities (cont.)
6.3 Intangible assets Note 2026 2025 $’000 $’000
Goodwill 6.3.2 12,383 12,383
12,383 12,383
Rent rolls 6.3.4a 26,654 26,448 Accumulated amortisation (23,978) (22,454)
2,676 3,994
Others 1,933 1,561 Accumulated amortisation and impairment (790) (615)
1,143 946
Total intangibles 16,202 17,323
6.3.1 Movements in Carrying Note Goodwill Rent rolls Other Total Amounts $’000 $’000 $’000 $’000 Carrying amount at 1 July 2024 12,383 7,408 770 20,561 Additions – 480 371 851 Disposals – – – – Amortisation expense – (3,894) (195) (4,089)
Carrying amount at 30 June 2025 12,383 3,994 946 17,323 – – – –
Carrying amount at 1 July 2025 12,383 3,994 946 17,323 Additions – 206 372 578 Disposals – – – – Amortisation expense – (1,524) (175) (1,699)
Carrying amount at 30 June 2026 12,383 2,676 1,143 16,202 – – – –
P a g e | 43
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 6 Non-financial assets and financial liabilities (cont.)
6.3 Intangible assets (cont.) 6.3.2 Allocation of goodwill to cash-generating units (CGU) Goodwill has been allocated for impairment testing purposes to the CGU. Before recognition of impairment losses, the carrying amount of goodwill was allocated to CGU as follows. 2026 2025 $’000 $’000 ◼ Top Level Real Estate – Residential sales 10,658 10,658 ◼ The Agency Tasmania – Residential sales 1,679 1,679 ◼ Settlements 46 46
Carrying amount as at 30 June 12,383 12,383 – – The recoverable amount of the Group’s Top Level Real Estate and The Agency Tasmania CGUs have been determined based on a value in use calculation which uses cash flow projections based on financial budgets approved by Directors utilising the following key assumptions: ◼ FY2027 approved budget has been used as a basis to determine cash flows in year 1, with a 2.5% growth used for year 2, rising to 5% for subsequent years; and ◼ Discount rate is based upon a weighted average cost of capital of 15%. The Directors believe that any reasonably possible further change in the key assumptions on which recoverable amount is based would not cause the Top Level Real Estate CGU or The Agency Tasmania CGU carrying amounts to exceed their recoverable amounts. 6.3.3 Accounting policy a. Intangible assets acquired separately Intangible assets acquired separately are recorded at cost less accumulated amortisation and impairment. Amortisation is charged on a straight-line basis over their estimated useful lives. The estimated useful life and amortisation method is reviewed at the end of each annual reporting period, with any changes in these accounting estimates being accounted for on a prospective basis.
b. Intangible assets acquired in a business combination Intangible assets acquired as part of a business combination, other than goodwill, are initially measured at their fair value at the date of the acquisition. Intangible assets acquired separately are initially recognised at cost. Indefinite life intangible assets are not amortised and are subsequently measured at cost less any impairment. Finite life intangible assets are subsequently measured at cost less amortisation and any impairment. The gains or losses recognised in profit or loss arising from derecognition of intangible assets are measured as the difference between net disposal proceeds and the carrying amount of the intangible asset. The method and useful lives of finite life intangible assets are reviewed annually. Changes in the expected pattern of consumption or useful life are accounted for prospectively by changing the amortisation method or period.
c. Trail Book intangible assets Trail book contracts and licences have a finite useful life and are carried at cost less accumulated amortisation and impairment losses. Amortisation is calculated using the straight-line method to allocate the cost of trail book and licences over their estimated useful lives.
d. Property Management intangible assets The property management rights are expected to have a finite life and are therefore amortised over their useful lives. The investment is carried at cost less accumulated amortisation and impairment losses. Amortisation is calculated using the straight-line method to allocate the cost of the rent roll over its estimated useful life which is based on comparable market evidence.
e. Business and domain names Business and domain names are recognised at cost of acquisition. They have a finite useful life and are amortised on a systematic basis based on the future economic benefits to be obtained over its useful life. Amortisation is calculated using the straight-line method.
P a g e | 44
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 6 Non-financial assets and financial liabilities (cont.)
6.3 Intangible assets (cont.) f. Subsequent measurement The following useful lives are used in the calculation of amortisation: Class 2026 2025 % % ◼ Rent rolls 15 15 ◼ Business and domain names 10 10
g. Goodwill Goodwill arising on an acquisition of a business is carried at cost as established at the date of the acquisition of the business (see note 13.1.1) less accumulated impairment losses, if any. For the purposes of impairment testing, goodwill is allocated to each of the Group’s cash-generating units (CGU) (or groups of CGUs) that is expected to benefit from the synergies of the combination. A CGU to which goodwill has been allocated is tested for impairment annually, or more frequently when there is an indication that the unit may be impaired. If the recoverable amount of the CGU is less than its carrying amount, the impairment loss is allocated first to reduce the carrying amount of any goodwill allocated to the unit and then to the other assets of the unit pro rata based on the carrying amount of each asset in the unit. Any impairment loss for goodwill is recognised directly in profit or loss. An impairment loss recognised for goodwill is not reversed in subsequent periods. On disposal of the relevant CGU, the attributable amount of goodwill is included in the determination of the profit or loss on disposal. 6.3.4 Key estimates and critical judgements – Impairment of intangibles a. Impairment of goodwill and rent rolls Determining whether goodwill is impaired requires an estimation of the value-in-use of the cash generating units (CGU) to which goodwill has been allocated. The value-in-use calculation requires management to estimate the future cash flows expected to arise from the CGU and a suitable discount rate in order to calculate present value. Where the actual future cash flows are less than expected, an impairment loss may arise. Included within the Agency Tasmania CGU (acquired in 2023) is a rent roll asset of $2,025K (2025: $2,761K). This same CGU also included goodwill of $1,679K, relating to sales (2025: $1,679K). Included within the Top Level CGU (acquired in 2019) is a rent roll asset of $564K (2025: $1,111K). This same CGU also included goodwill of $10,658K, relating to sales (2025: $10,658K). For the rent roll assets, the recoverable amounts of these CGU’s are derived from market transactional evidence in relation to their fair value. Management have determined that a multiple of 3.8 for residential property and 2.75 for commercial property for the Top Level CGU (based on an independent expert opinion), multiplied by the annual rent roll income is an appropriate measure of the fair value of the rent roll assets. Fair value less cost to sell of the CGU was classified on a level 3 basis, under AASB 13. No impairment resulted. Management performed a goodwill impairment test of the CGUs taking a conservative approach in preparing its value in use calculation in light of market uncertainty resulting from increases in interest rates to curb inflationary pressures. Management applied a discount rate of 15% resulting in no impairment loss for 2026 (2025: 15%). To evaluate the recoverable amount of the CGUs, a terminal value has been assumed after the fifth year and includes a growth rate in the cash flow of 5% into perpetuity (2025: 5%) based upon a Board approved forecast. The discount rates used reflect the risks specific to the CGUs. The Group has performed sensitivity analysis on the impairment testing of its CGUs by assessing reasonably possible changes in key assumptions. The analysis considered adverse movements in both the discount rate and long-term growth rate. The testing included up to a 3% increase in discount rate and a 3% reduction in long-term growth rate. The results of the sensitivity analysis indicate that sufficient headroom remains under a combined scenario of a 2% reduction in the long- term growth rate and a 3% increase in the discount rate. The analysis also indicates that sufficient headroom remains under a standalone reduction of up to 3% in the long-term growth rate.
P a g e | 45
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 6 Non-financial assets and financial liabilities (cont.)
6.4 Provisions 2026 2025 $’000 $’000 6.4.1 Current Employee entitlements 3,612 2,943 Future fund referrals 648 510
4,260 3,453 6.4.2 Non-current Employee entitlements 141 185 Make good provisions 200 150 Future fund referrals 53 67
394 402
6.4.3 Movements in Carrying Amounts Employee Make good Future fund entitlements provisions referrals Total $’000 $’000 $’000 $’000
Carrying amount at 1 July 2025 – 3,128 150 577 3,855 Additions 2,869 – – 2,869 Acquisitions – 50 124 174 Amounts used during the year (2,244) – – (2,244)
Carrying amount at 30 June 2026 3,753 200 701 4,654 – – – –
6.4.4 Description of provisions a. Provision for employee benefits represents amounts accrued for annual leave (AL) and long service leave (LSL). The current portion for this provision includes the total amount accrued for AL entitlements and the amounts accrued for LSL entitlements that have vested due to employees having completed the required period of service. The Group does not expect the full amount of AL or LSL balances classified as current liabilities to be settled within the next 12 months. However, these amounts must be classified as current liabilities since the Group does not have an unconditional right to defer the settlement of these amounts in the event employees wish to use their leave entitlement. b. Make good provision. The Company is required to restore the leased premises to their original condition at the end of the respective lease terms. A make good provision has been recognised for the present value of the estimated expenditure required to remove any leasehold improvements. The Directors valued the make good provision based upon a third-party cost estimate provided to the Company. c. Provision for future fund referrals is an incentive scheme provided to property partners for successfully referring property management and mortgage broking transactions. The referral fees are transferred into an asset growth model which creates an interest in the future benefit of the Property Partner, maturing after two years, which also assists to retain staff. The company estimates the value of the future fund referral provision using a probability weighting model which is based on historic information.
6.4.5 Accounting policy Provisions are recognised when the Group has a present obligation (legal or constructive) as a result of a past event, it is probable that an outflow of resources embodying economic benefits will be required to settle the obligation and a reliable estimate can be made of the amount of the obligation. Provisions are not recognised for future operating losses. When the Group expects some or all of a provision to be reimbursed, for example under an insurance contract, the reimbursement is recognised as a separate asset but only when the reimbursement is virtually certain. The expense relating to any provision is presented in the statement of comprehensive income net of any reimbursement. Provisions are measured at the present value or management’s best estimate of the expenditure required to settle the present obligation at the end of the reporting period.
P a g e | 46
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 6 Non-financial assets and financial liabilities (cont.)
6.4 Provisions (cont.) If the effect of the time value of money is material, provisions are discounted using a current pre-tax rate that reflects the risks specific to the liability. When discounting is used, the increase in the provision due to the passage of time is recognised as an interest expense. Provision is made for the amount of any dividend declared, being appropriately authorised and no longer at the discretion of the entity, on or before the end of the reporting period but not distributed at the end of the reporting date.
6.5 Other material accounting policies related to non-financial assets and liabilities
6.5.1 Impairment of non-financial assets The carrying amounts of the Group’s non-financial assets, other than deferred tax assets (see accounting policy at note 4.9) are reviewed at each reporting date to determine whether there is any indication of impairment. If any such indication exists, then the asset’s recoverable amount is estimated. Goodwill and intangible assets that have an indefinite useful life are not subject to amortisation and are tested annually for impairment or more frequently if events or changes in circumstances indicate that they might be impaired. Other assets are reviewed for impairment whenever events or changes in circumstances indicate that the carrying amount may not be recoverable. An impairment loss is recognised when the carrying amount of an asset or cash-generating unit exceeds its recoverable amount. A cash-generating unit is the smallest identifiable group of assets that generates largely independent cash flows. Impairment losses are recognised in the income statement unless the asset has previously been revalued, in which case the loss is recognised as a reversal up to the amount of the prior revaluation, with any excess recognised in the income statement. Losses for cash-generating units are allocated first to reduce goodwill and then to other assets in the unit on a pro rata basis. The recoverable amount of an asset or cash-generating unit is the higher of fair value less costs to sell and value in use. Value in use is calculated by discounting estimated future cash flows to present value using a pre-tax discount rate reflecting current market assessments of the time value of money and asset-specific risks. For assets that do not generate largely independent cash inflows, the recoverable amount is determined for the cash-generating unit to which they belong. Impairment losses recognised in prior periods are assessed at each reporting date for indications that the loss has decreased or no longer exists. An impairment loss is reversed if there has been a change in the estimates used to determine the recoverable amount, and only to the extent that the asset’s carrying amount does not exceed the amount that would have been determined, net of depreciation and amortisation, if no impairment loss had been recognised.
Note 7 Equity
7.1 Issued capital Note 2026 2025 2026 2025 No. No. $’000 $’000
Fully paid ordinary shares 439,575,921 439,575,921 44,163 44,163
2026 2025 2026 2025 7.1.1 Ordinary shares No. No. $’000 $’000 At the beginning of the year 439,575,921 428,575,921 44,163 43,635 Shares issued during the year: – – – – ◼ Conversion of performance rights 7.2 – 11,000,000 – 528 Transaction costs relating to share issues – – – –
At reporting date 439,575,921 439,575,921 44,163 44,163
7.1.2 Ordinary shares entitle the holder to participate in dividends and the proceeds on winding up of the Company in proportion to the number of and amounts paid on the shares held. On a show of hands every holder of ordinary shares present at a meeting in person or by proxy, is entitled to one vote, and upon a poll each share is entitled to one vote. Ordinary shares have no par value, and the Company does not have a limited amount of authorised capital. 7.1.3 Accounting policy Ordinary issued capital is recorded at the consideration received. Incremental costs directly attributable to the issue of ordinary shares and share options are recognised as a deduction from equity, net of any related income tax benefit. Ordinary issued capital bears no special terms or conditions affecting income or capital entitlements of the shareholders.
P a g e | 47
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 7 Equity (cont.)
7.2 Performance equity Note 2026 2025 2026 2025 No. No. $’000 $’000
Performance equity – – – –
2026 2025 2026 2025 7.2.1 Performance equity movement No. No. $’000 $’000 At the beginning of the year – 11,000,000 – 528 Performance equity changes during the year: ◼ Expense of issued performance – – – rights ◼ Conversion of performance rights 7.1 – (11,000,000) – (528)
At reporting date – – – –
7.3 Options Note 2026 2025 2026 2025 No. No. $’000 $’000
Options 1,500,000 1,500,000 50 50
2026 2025 2026 2025 7.3.1 Options equity movement No. No. $’000 $’000 At the beginning of the year 1,500,000 11,500,000 50 409 Options movement during the year: ◼ Expiry of options – (10,000,000) – (359)
At reporting date 1,500,000 1,500,000 50 50
7.4 Reserves Note 2026 2025 $’000 $’000 Share-based payment reserve: – –
◼ Performance rights 7.2 – – ◼ Options 7.3 50 50
50 50 7.4.1 Share-based payment reserve The share-based payment reserve records the value of options and performance shares or rights issued by the Company to its employees or consultants.
P a g e | 48
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
SECTION B. RISK This section of the notes discusses the Group’s exposure to various risks and shows how these could affect the Group’s financial position and performance.
Note 8 Financial risk management 8.1 Financial risk management policies This note presents information about the Group’s exposure to each of the above risks, its objectives, policies and procedures for measuring and managing risk, and the management of capital. The Group’s financial instruments consist mainly of deposits with banks, short-term investments, and accounts payable and receivable. The Group does not speculate in the trading of derivative instruments. A summary of the Group’s financial assets and liabilities is shown below: Floating Fixed Non- Floating Fixed Non- interest interest interest- 2026 interest interest interest- 2025 rate rate bearing Total rate rate bearing Total $’000 $’000 $’000 $’000 $’000 $’000 $’000 $’000 Financial assets ◼ Cash and cash equivalents 4,243 – – 4,243 5,065 – – 5,065 ◼ Trade and other receivables – – 14,183 14,183 – – 14,667 14,667 ◼ Bank guarantees – 1,119 – 1,119 – 1,001 – 1,001 ◼ Investments – – 75 75 – – – –
Total Financial Assets 4,243 1,119 14,258 19,620 5,065 1,001 14,667 20,733
Financial liabilities at amortised cost ◼ Trade and other payables – – 20,275 20,275 – – 20,988 20,988 ◼ Borrowings 8,400 – – 8,400 8,400 – – 8,400 ◼ Leases – 7,761 – 7,761 – 8,950 – 8,950 ◼ Financial liabilities (convertible notes) 5,533 – – 5,533 4,293 – – 4,293
Total Financial Liabilities 13,933 7,761 20,275 41,969 12,693 8,950 20,988 42,631
Net Financial Assets / (Liabilities) (9,690) (6,642) (6,017) (22,349) (7,628) (7,949) (6,321) (21,898)
8.2 Specific financial risk exposures and management The main risks the Group is exposed to through its financial instruments are credit risk, liquidity risk, and market risk consisting of interest rate, foreign currency risk, and equity price risk. The Group’s overall risk management program focuses on the unpredictability of financial markets and seeks to minimise potential adverse effects on the financial performance of the Group. The Board has overall responsibility for the establishment and oversight of the risk management framework. The Board adopts practices designed to identify significant areas of business risk and to effectively manage those risks in accordance with the Group’s risk profile. This includes assessing, monitoring and managing risks for the Group and setting appropriate risk limits and controls. The Group is not of a size nor is its affairs of such complexity to justify the establishment of a formal system for risk management and associated controls. Risk management is carried out by the full Board as the Group believes that it is crucial for all board members to be involved in this process. The Chairman, with the assistance of senior management as required, has responsibility for identifying, assessing, treating and monitoring risks and reporting to the Board on risk management.
P a g e | 49
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 8 Financial risk management (cont.) 8.2.1 Credit risk Exposure to credit risk relating to financial assets arises from the potential non-performance by counterparties of contract obligations that could lead to a financial loss to the Group. Credit risk is the risk that a counterparty will default on its contractual obligations, resulting in financial loss to the Group. The Group has adopted a policy of only dealing with creditworthy counterparties and obtaining sufficient collateral where appropriate to mitigate the risk of financial loss from defaults. The Group only transacts with entities rated investment grade and above. This information is supplied by independent rating agencies where available, and if not, the Group uses publicly available financial information and its own trading record to rate major customers. The Group’s exposure and counterparties’ credit ratings are continuously monitored, and transactions are spread amongst approved counterparties. Credit exposure is controlled by counterparty limits reviewed and approved annually by the Board. The Group establishes an allowance for impairment that represents its estimate of incurred losses in respect of trade and other receivables.
◼ Credit risk exposures The maximum exposure to credit risk, arising from cash and cash equivalents and trade receivables, is limited to the carrying amount, net of any provisions for impairment of those assets, as disclosed in the statement of financial position and notes to the financial statements. Credit risk related to balances with banks and other financial institutions is managed by the Group in accordance with approved Board policy. Such policy requires that surplus funds are only invested with financial institutions residing in Australia, wherever possible. There are no significant concentrations of credit risk, whether through exposure to individual customers, specific industry sectors and/or regions.
◼ Impairment losses The ageing of the Group’s current trade and other receivables at reporting date was as follows: Past due but Past due but Gross Impaired Net not impaired Gross Impaired Net not impaired 2026 2026 2026 2026 2025 2025 2025 2025 $’000 $’000 $’000 $’000 $’000 $’000 $’000 $’000 Trade receivables Not past due 9,479 9,479 – 10,184 – 10,184 – Past due up to 30 days 813 – 813 813 460 – 460 460 Past due 31 days to 90 days 321 – 321 321 152 – 152 152 Past due over 90 days 1,462 (200) 1,262 1,262 1,026 (483) 543 543 12,075 (200) 11,875 2,396 11,822 (483) 11,339 1,155 Other receivables Not past due(IV) 2,568 (260) 2,308 – 3,453 (125) 3,328 –
Total – – 14,643 (460) 14,183 2,396 15,275 (608) 14,667 1,155
Included in the aged trade receivables are invoices raised for commissions on property developments which are unconditional but payable upon completion. 8.2.2 Liquidity risk Liquidity risk is the risk that the Group will be unable to meet its financial obligations as they fall due. The Group’s approach is to ensure it always has sufficient liquidity to meet liabilities under both normal and stressed conditions without incurring unacceptable losses or reputational damage. Ultimate responsibility for liquidity risk management rests with the Board, which has established an appropriate framework for managing the Group’s short, medium and long-term funding and liquidity needs. The Group manages liquidity risk by maintaining adequate reserves and facilities, continuously monitoring forecast and actual cash flows, and matching the maturity profiles of financial assets and liabilities. The Group’s ability to raise debt and/or equity funding in the market remains paramount.
(IV) Items within the trade and other receivables and trade and other payables have been reclassified between line items to better reflect their nature, and comparative figures have been reclassified accordingly; these changes had no impact on net profit, earnings per share or net assets.
P a g e | 50
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 8 Financial risk management (cont.) The Group has access to the undrawn balance of its $10.0 million financing facility with Macquarie Bank Limited. As at the reporting date, $8.4 million of the facility had been drawn, leaving $1.6 million available for future draw down, as detailed in note 5.6.3. The non-interest-bearing financial liabilities the Group had at the end of the reporting period were trade and other payables incurred in the normal course of the business. These were due within the normal 30-60 days terms of creditor payments. Interest-bearing liabilities of the Group comprised borrowings (note 5.6), convertible notes (note 5.7), and leases (note 6.2).
◼ Contractual Maturities The table below analyses the Group’s financial liabilities and assets into relevant maturity groupings based on the remaining period at the end of the reporting period to the contractual maturity date. The amounts disclosed in the table are the undiscounted contractual cash flows: Within 1 year Greater than 1 year Total 2026 2025 2026 2025 2026 2025 $’000 $’000 $’000 $’000 $’000 $’000 Financial liabilities due for payment ◼ Trade and other payables(V) 20,275 20,988 – – 20,275 20,988 ◼ Borrowings – 8,400 8,400 – 8,400 8,400 ◼ Financial liabilities – convertible notes 5,533 4,293 – – 5,533 4,293 ◼ Leases 2,397 2,440 5,364 6,510 7,761 8,950
Total contractual outflows 28,205 36,121 13,764 6,510 41,969 42,631 Financial assets ◼ Cash and cash equivalents 4,243 5,065 – – 4,243 5,065 ◼ Trade and other receivables(V) 13,118 14,247 1,065 420 14,183 14,667 ◼ Bank guarantees and restricted cash – – 1,119 1,001 1,119 1,001 ◼ Investments – – 75 – 75 –
Total anticipated inflows 17,361 19,312 2,259 1,421 19,620 20,733
Net outflow on financial instruments (10,844) (16,809) (11,505) (5,089) (22,349) (21,898)
It is not expected that the cash flows included in the maturity analysis could occur significantly earlier or at significantly different amounts.
8.2.3 Market risk Market risk is the risk that changes in market prices, such as foreign exchange rates, interest rates and equity prices will affect the Group’s income or the value of its holdings of financial instruments. The objective of market risk management is to manage and control market risk exposures within acceptable parameters, while optimising the return. The Group’s activities minimally expose it to the financial risks of changes in foreign currency exchange rates, commodity prices and exchange rates. The Group does not enter into derivative financial instruments including foreign exchange forward contracts to hedge against financial risk. There has been no change to the Group’s exposure to market risks or the manner in which it manages and measures the risk from the previous period.
a. Interest rate risk The Group is exposed to interest rate risk as the Group borrows funds at both fixed and floating interest rates. The risk is managed by the Group by maintaining an appropriate mix between fixed and floating rate borrowings. The Group’s policy is to monitor the interest rate yield curve out to six months to maintain a balance between liquidity of cash assets and interest income. Cash at bank earns interest at floating rates based on daily deposit rates. The Group has no receivables or payables subject to interest rate risk.
b. Foreign exchange risk The Group is not exposed to any material foreign exchange risk. (V) Items within the trade and other receivables and trade and other payables have been reclassified between line items to better reflect their nature, and comparative figures have been reclassified accordingly; these changes had no impact on net profit, earnings per share or net assets.
P a g e | 51
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 8 Financial risk management (cont.) c. Price risk Price risk relates to the risk that the fair value or future cash flows of a financial instrument will fluctuate because of changes in market prices. The Group does not presently hold material amounts subject to price risk. As such the Board considers price risk as a low risk to the Group.
8.2.4 Sensitivity analyses A general change of ±100 basis points change in interest rate would be expected to have ±$97K impact on earnings (2025: ±$76K). The Group is not exposed to any other material sensitivities.
8.2.5 Net fair values a. Fair value estimation The fair values of financial assets and liabilities are shown in note 8.1 and can be compared to their carrying amounts in the statement of financial position. Fair value represents the amount at which an asset could be exchanged, or a liability settled, between knowledgeable, willing parties in an arm’s length transaction.
Financial instruments whose carrying value is equivalent to fair value due to their nature include: ◼ Cash and cash equivalents; ◼ Trade and other receivables; and ◼ Trade and other payables.
The methods and assumptions used in determining the fair values of financial instruments are disclosed in the accounting policy notes specific to the asset or liability.
Note 9 Capital management 9.1 Capital The Group manages its capital to ensure that entities in the Group will be able to continue as a going concern while maximising the return to stakeholders through the optimisation of the debt and equity balance. Capital is defined as contributed equity, reserves and net debt (borrowings less cash). The Board monitors and approves the capital management framework within which management operates. The Group’s objective is to safeguard its ability to continue as a going concern, providing returns for shareholders and benefits for stakeholders. Key parameters such as gearing, earnings growth, cost and maturity of debt, and borrowing capacity are considered when allocating capital and evaluating investments. The capital structure of the Group can be changed by paying distributions to shareholders, returning capital to shareholders, issuing new shares or selling assets.
9.2 Working capital Note 2026 2025 The working capital position of the Group was as follows: $’000 $’000
Cash and cash equivalents 5.1 4,243 5,065 Trade and other receivables(VI) 5.2.1 13,118 14,247 Other current assets 5.4.1 2,138 1,096 Trade and other payables(VI) 5.5.1 (20,275) (20,988) Borrowings 5.6.1 – (8,400) Financial liabilities 5.7.1 (5,533) (4,293) Leases 6.2.2 (2,397) (2,440) Current provisions 6.4 (4,260) (3,453)
Working capital position (12,966) (19,166)
(VI) Items within the trade and other receivables and trade and other payables have been reclassified between line items to better reflect their nature, and comparative figures have been reclassified accordingly; these changes had no impact on net profit, earnings per share or net assets.
P a g e | 52
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
SECTION C. GROUP STRUCTURE This section provides information which will help users understand how the Group structure affects the financial position and performance of the Group as a whole. In particular, there is information about: (a) changes to the structure that occurred during the year due to business combinations and disposal of a discontinued operation. (b) transactions with non-controlling interests, and (c) interests in joint operations. A list of significant subsidiaries is provided in note 10 below. Note 10 Interest in subsidiaries The subsidiaries listed below have ordinary shares which are held directly by the Group and the proportion of ownership interest held equals the voting rights held by the Group. Investments in subsidiaries are accounted for at cost. Entity name Class of Percentage owned Country of Shares incorporation 2026 2025 ◼ Agency Partners WA Pty Ltd Ordinary 100 100 Australia ◼ Ausnet Financial Planning Services Pty Ltd Ordinary 100 100 Australia ◼ Ausnet Financial Pty Ltd Ordinary 100 100 Australia ◼ Ausnet Property Investment Fund Pty Ltd Ordinary 100 100 Australia ◼ Ausnet Real Estate Services Pty Ltd Ordinary 100 100 Australia ◼ Courtesy Real Estate (NSW) Pty Ltd Ordinary 100 100 Australia ◼ Jelina Holdings Pty Ltd Ordinary 100 100 Australia ◼ Move Property Solutions Pty Ltd Ordinary 100 100 Australia ◼ S.J. Laing & Son Pty Ltd Ordinary 100 100 Australia ◼ The Agency Auctions NSW Pty Ltd Ordinary 100 100 Australia ◼ The Agency Canberra Pty Ltd Ordinary 100 100 Australia ◼ The Agency Commercial Real Estate Pty Ltd(1) Ordinary 0 100 Australia ◼ The Agency Marketing Pty Ltd Ordinary 100 100 Australia ◼ The Agency MDC QLD Pty Ltd Ordinary 100 100 Australia ◼ The Agency MDC Pty Ltd Ordinary 100 100 Australia ◼ The Agency Project Sales NSW Pty Ltd Ordinary 100 100 Australia ◼ The Agency Project Sales QLD Pty Ltd Ordinary 100 100 Australia ◼ The Agency Project Sales VIC Pty Ltd Ordinary 100 100 Australia ◼ The Agency Property Management NSW Pty Ltd Ordinary 100 100 Australia ◼ The Agency Real Estate Pty Ltd Ordinary 100 100 Australia ◼ The Agency Sales NSW Pty Ltd Ordinary 100 100 Australia ◼ The Agency Sales QLD Pty Ltd Ordinary 100 100 Australia ◼ The Agency Sales VIC Pty Ltd Ordinary 100 100 Australia ◼ The Agency Strata Pty Ltd Ordinary 100 100 Australia ◼ The Agency Tasmania Pty Ltd Ordinary 100 100 Australia ◼ The Real Estate Group Australia Pty Ltd Ordinary 100 100 Australia ◼ Top Level Real Estate Holdings Pty Ltd Ordinary 100 100 Australia ◼ Top Level Real Estate Pty Ltd Ordinary 100 100 Australia ◼ Top Level Real Estate Sales Pty Ltd Ordinary 100 100 Australia ◼ Value Partner Program Pty Ltd Ordinary 100 100 Australia ◼ Vision Capital Management Ltd Ordinary 100 100 Australia (1) The Agency Commercial Real Estate Pty Ltd, a dormant subsidiary, was disposed of during the year for nil consideration. No gain or loss was recognised and the disposal had no financial effect on the consolidated financial statements.
P a g e | 53
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 11 Investment accounted for using the equity method Note 2026 2025 $’000 $’000 11.1 Non-current ◼ Westvalley Corporation Pty Ltd 11.3.3 289 350
289 350
11.2 Information about associates The Group held a 20% equity interest in Westvalley Corporation Pty Ltd (Westvalley). The Group’s interest in Westvalley was accounted for using the equity method in the consolidated financial statements as the Group does not control or have joint control over Westvalley. On 1 July 2026, Oxygen Capital Group Pty Ltd (Oxygen) acquired the remaining 20% interest in Westvalley from Ausnet Real Estate Services Pty Ltd. As consideration for the acquisition, Oxygen issued 2,677,864 ordinary shares at an issue price of $0.1078 per share. Following completion of the transaction, Ausnet Real Estate Services Pty Ltd held approximately 2.2% interest in Oxygen. Country of Percentage Owned Incorporation 2026 2025 ◼ Westvalley Corporation Pty Ltd Australia 20 20
11.3 Summarised financial information Summarised financial information of the Group’s share in Westvalley is as follows:
2026 2025 11.3.1 Summarised financial position $’000 $’000
Current assets 147 281 Current liabilities (219) (448) Current net assets (72) (167)
Non‐current assets ‐ ‐ Non‐current liabilities ‐ ‐ Non‐current net assets ‐ ‐
Net assets (72) (167)
2026 2025 11.3.2 Summarised financial performance $’000 $’000
Revenue and other income 819 1,370 Cost of sales (77) (463) Administrative expenses (643) (368) Income tax benefit / (expense) (25) (162)
Total comprehensive income 74 377 Group’s share of associate’s profit after tax 15 75 Group’s share of associate’s other comprehensive income ‐ ‐
2026 2025 11.3.3 Reconciliation to carrying amounts: $’000 $’000 Opening net assets at fair value 350 300 Fair value of interest acquired during the period ‐ ‐ Share of profit for year 11.3.2 15 75 Less: dividends received (76) (25)
Closing net assets (carrying amount of investment) 289 350
P a g e | 54
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 12 Parent entity disclosures The Agency Group Australia Ltd is the ultimate Australian parent entity and ultimate parent of the Group. The Agency Group Australia Ltd did not enter into any trading transactions with any related party during the year.
12.1 Financial position of The Agency Group Australia Ltd 2026 2025 $’000 $’000
Current assets 663 1,436 Non-current assets 4,583 3,384
Total assets 5,246 4,820
Current liabilities 5,246 4,820 Non-current liabilities – –
Total liabilities 5,246 4,820
Net assets – –
Equity Issued capital 44,163 44,163 Share-based payment reserve 50 50 Accumulated losses (44,213) (44,213)
Total equity – –
12.2 Financial performance of The Agency Group Australia Ltd 2026 2025 $’000 $’000
Loss for the year – – Other comprehensive income – –
Total comprehensive income 12.2.1 – –
12.2.1 The parent entity does not carry on trading operations. Its principal assets are its investment in subsidiaries and amounts receivable from wholly owned subsidiaries, the recovery of which is dependent on the future cash flows generated by the Group. The Directors have assessed the recoverable amount of the investment in subsidiaries as $nil in accordance with AASB 136 Impairment of Assets, and have no reasonable expectation of recovering the amounts receivable from subsidiaries within the meaning of AASB 9 Financial Instruments. Accordingly, both are carried at $nil. Operating and finance costs of $5.3 million incurred by the parent entity during the year (2025: $4.9 million) were offset by a corresponding reduction in the impairment recognised against those balances, and the parent entity therefore recorded no profit or loss for the year (2025: $nil).
12.3 Contractual commitments The parent company has no capital commitments at 2026 (2025: $nil). The parent company’s other commitments are disclosed in note 14 Commitments. 12.4 Contingent liabilities and guarantees There are no guarantees entered into by The Agency Group Australia Ltd for the debts of its subsidiaries as at 2026 (2025: none). The parent company’s other contingencies are disclosed in note 15 Contingent liabilities.
P a g e | 55
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 13 Other material accounting policies related to the Group structure
13.1 Basis of consolidation As at reporting date, the assets and liabilities of all controlled entities have been incorporated into the consolidated financial statements as well as their results for the year then ended. Where controlled entities have entered (left) the Consolidated Group during the year, their operating results have been included (excluded) from the date control was obtained (ceased).
13.1.1 Business combinations Acquisitions of businesses are accounted for using the acquisition method. The consideration transferred in a business combination is measured at fair value, which is calculated as the sum of the acquisition‑date fair values of assets transferred by the Group, liabilities incurred by the Group to the former owners of the acquiree and the equity interest issued by the Group in exchange for control of the acquiree. Acquisition‑related costs are recognised in profit or loss as incurred. At the acquisition date, the identifiable assets acquired and the liabilities assumed are recognised at their fair value at the acquisition date, except that: ◼ deferred tax assets or liabilities and assets or liabilities related to employee benefit arrangements are recognised and measured in accordance with AASB 112 Income Taxes and AASB 119 Employee Benefits respectively; ◼ liabilities or equity instruments related to share‑based payment arrangements of the acquiree or share‑based payment arrangements of the Group entered into to replace share‑based payment arrangements of the acquiree are measured in accordance with AASB 2 Share‑Based Payments at the acquisition date; and ◼ assets (or disposal groups) that are classified as held for sale in accordance with AASB 5 Non‑current Assets Held for Sale and Discontinued Operations are measured in accordance with that Standard.
a. Goodwill Goodwill is measured as the excess of the sum of the consideration transferred, the amount of any non‑controlling interests in the acquiree, and the fair value of the acquirer’s previously held equity interest in the acquiree (if any) over the net of the acquisition‑date amounts of the identifiable assets acquired and the liabilities assumed. If, after reassessment, the net of the acquisition‑date amounts of the identifiable assets acquired and liabilities assumed exceeds the sum of the consideration transferred, the amount of any non‑controlling interests in the acquiree and the fair value of the acquirer’s previously held interest in the acquiree (if any), the excess is recognised immediately in profit or loss as a bargain purchase gain. When the consideration transferred by the Group in a business combination includes a contingent consideration arrangement, the contingent consideration is measured at its acquisition‑date fair value and included as part of the consideration transferred in a business combination. Changes in fair value of the contingent consideration that qualify as measurement period adjustments are adjusted retrospectively, with corresponding adjustments against goodwill. Measurement period adjustments are adjustments that arise from additional information obtained during the measurement period (which cannot exceed one year from the acquisition date) about facts and circumstances that existed at the acquisition date. The subsequent accounting for changes in the fair value of the contingent consideration that do not qualify as measurement period adjustments depends on how the contingent consideration is classified. Contingent consideration that is classified as equity is not remeasured at subsequent reporting dates and its subsequent settlement is accounted for within equity. Other contingent consideration is remeasured to fair value at subsequent reporting dates with changes in fair value recognised in profit or loss. When a business combination is achieved in stages, the Group’s previously held interests in the acquired entity are remeasured to its acquisition‑date fair value and the resulting gain or loss, if any, is recognised in profit or loss. Amounts arising from interests in the acquiree prior to the acquisition date that have previously been recognised in OCI are reclassified to profit or loss, where such treatment would be appropriate if that interest were disposed of. If the initial accounting for a business combination is incomplete by the end of the reporting period in which the combination occurs, the Group reports provisional amounts for the items for which the accounting is incomplete. Those provisional amounts are adjusted during the measurement period, or additional assets or liabilities are recognised, to reflect new information obtained about facts and circumstances that existed as of the acquisition date that, if known, would have affected the amounts recognised as of that date. b. Intangible assets acquired in a business combination Intangible assets acquired in a business combination and recognised separately from goodwill are recognised initially at their fair value at the acquisition date (which is regarded as their cost). Subsequent to initial recognition, intangible assets acquired in a business combination are reported at cost less accumulated amortisation and impairment losses, on the same basis as intangible assets that are acquired separately.
P a g e | 56
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 13 Other material accounting policies related to the Group structure (cont.) c. Contingent liabilities acquired in a business combination Contingent liabilities acquired in a business combination are initially measured at fair value at the acquisition date. At the end of subsequent reporting periods, such contingent liabilities are measured at the higher of the amount that would be recognised in accordance with AASB 137 Provisions, Contingent Liabilities and Contingent Assets and the amount recognised initially less cumulative amount of income recognised in accordance with the principles of AASB 15 Revenue from Contracts with Customers.
13.1.2 Subsidiaries Subsidiaries are entities controlled by the Group. The financial statements of subsidiaries are included in the consolidated financial statements from the date that control commences until the date that control ceases. The accounting policies of subsidiaries have been changed when necessary to align them with policies adopted by the Group. Equity interests in a subsidiary not attributable, directly or indirectly, to the Group are presented as non-controlling interests. The Group initially recognises non-controlling interests that are present ownership interests in subsidiaries and are entitled to a proportionate share of the subsidiary’s net assets on liquidation at either fair value or at the non-controlling interests’ proportionate share of the subsidiary’s net assets. Subsequent to initial recognition, non-controlling interests are attributed their share of profit or loss and each component of other comprehensive income. Non-controlling interests are shown separately within the equity section of the statement of financial position and statement of comprehensive income. The grant by the Company of options over its equity instruments to the employees of subsidiary undertakings in the Group is treated as a capital contribution to that subsidiary undertaking. The fair value of employee services received, measured by reference to the grant date fair value, is recognised over the vesting period as an increase to investment in subsidiary undertakings, with a corresponding credit to equity. Losses applicable to the non-controlling interests in a subsidiary are allocated to the non-controlling interests even if doing so causes the non-controlling interests to have a deficit balance. A list of controlled entities is contained in note 10 Interest in subsidiaries of the financial statements.
13.1.3 Loss of control Upon the loss of control, the Group derecognises the assets and liabilities of the subsidiary, any non-controlling interests and the other components of equity related to the subsidiary. Any surplus or deficit arising on the loss of control is recognised in profit or loss. If the Group retains any interest in the previous subsidiary, then such interests are measured at fair value at the date control is lost. Subsequently it is accounted for as an equity-accounted investee or as an available-for-sale financial asset depending on the level of influence retained.
13.1.4 Transactions eliminated on consolidation All intra-group balances and transactions, and any unrealised income and expenses arising from intra-group transactions, are eliminated in preparing the consolidated financial statements.
13.1.5 Associates Associates are all entities over which the group has significant influence but not control or joint control. This is generally the case where the group holds between 20% and 50% of the voting rights. Investments in associates are accounted for using the equity method of accounting, after initially being recognised at cost.
a. Joint arrangements Under AASB 11 Joint Arrangements investments in joint arrangements are classified as either joint operations or joint ventures. The classification depends on the contractual rights and obligations of each investor, rather than the legal structure of the joint arrangement. A joint venture is an arrangement that the Group controls jointly with one or more other investors, and over which the Group has rights to a share of the arrangement’s net assets rather than direct rights to underlying assets and obligations for underlying liabilities. A joint arrangement in which the Group has direct rights to underlying assets and obligations for underlying liabilities is classified as a joint operation. b. Joint operations For joint operations, The Agency recognises its direct right to the assets, liabilities, revenues and expenses of joint operations and its share of any jointly held or incurred assets, liabilities, revenues and expenses. c. Joint ventures Interests in joint ventures are accounted for using the equity method, after initially being recognised at cost in the consolidated statement of financial position.
P a g e | 57
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 13 Other material accounting policies related to the Group structure (cont.) 13.1.6 Equity method Under the equity method of accounting, the investments are initially recognised at cost and adjusted thereafter to recognise the Group’s share of the post-acquisition profits or losses of the investee in profit or loss, and the group’s share of movements in other comprehensive income of the investee in other comprehensive income. Dividends received or receivable from associates and joint ventures are recognised as a reduction in the carrying amount of the investment. Where the Group’s share of losses in an equity-accounted investment equals or exceeds its interest in the entity, including any other unsecured long-term receivables, the Group does not recognise further losses, unless it has incurred obligations or made payments on behalf of the other entity. Unrealised gains on transactions between the Group and its associates and joint ventures are eliminated to the extent of the Group’s interest in these entities. Unrealised losses are also eliminated unless the transaction provides evidence of an impairment of the asset transferred. Accounting policies of equity-accounted investees have been changed where necessary to ensure consistency with the policies adopted by the Group. The carrying value of equity-accounted investments is tested for impairment in accordance with the policy described in note 6.5.1.
P a g e | 58
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
SECTION D. UNRECOGNISED ITEMS This section of the notes provides information about items that are not recognised in the financial statements as they do not (yet) satisfy the recognition criteria. In addition to the items and transactions disclosed below, there are also unrecognised tax amounts – see note 4 Income tax.
Note 14 Commitments There are no material commitments to the Group as at 30 June 2026 (2025: $Nil).
Note 15 Contingent liabilities There are no contingent liabilities as at 30 June 2026.
Note 16 Events subsequent to reporting date 16.1 Strategic Discussions with Aura Group As announced on 7 August 2026, The Agency has held discussions with Aura Group Holdings Pte Ltd (Aura Group) and other parties in relation to establishing and managing the Company’s rent roll fund and financing opportunities for rent roll acquisitions. Those discussions with Aura Group evolved to a potential transaction under which Aura Group made a confidential, non- binding and conditional proposal regarding a scrip-for-scrip merger, based on a current indicative transaction price of $0.04 per AU1 share and a valuation of Aura Group that remains under discussion, subject to Aura Group’s listing on ASX. The Board has provided Aura Group with a period of exclusivity to conduct due diligence and progress relevant transaction documentation. The proposal remains subject to negotiation and execution of definitive documentation, satisfactory mutual due diligence, regulatory approvals and other customary conditions. 16.2 Disposal of interest in Westvalley Corporation Pty Ltd (Westvalley) On 1 July 2026, Oxygen Capital Group Pty Ltd (Oxygen) acquired the remaining 20% interest in Westvalley from Ausnet Real Estate Services Pty Ltd. As consideration for the acquisition, Oxygen issued 2,677,864 ordinary shares at an issue price of $0.1078 per share. Following completion of the transaction, Ausnet Real Estate Services Pty Ltd held approximately 2.2% interest in Oxygen. There have been no other matters or circumstances that have arisen after balance date that have significantly affected, or may significantly affect, the operations of the Group, the results of those operations, or the state of affairs of the Group in future financial periods.
P a g e | 59
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
SECTION E. OTHER INFORMATION This section of the notes includes other information that must be disclosed to comply with the accounting standards and other pronouncements, but that is not immediately related to individual line items in the financial statements.
Note 17 Key management personnel (KMP) compensation The names and positions of KMP are as follows: ◼ Andrew Jensen Executive Chairman and Chief Operating Officer ◼ Paul Niardone Executive Director ◼ Adam Davey Non-Executive Director ◼ Michael Schaper Non-Executive Director ◼ Melissa Peters Non-Executive Director (appointed 1 May 2026) ◼ Other KMP: Matt Lahood CEO – Real Estate ◼ Former KMP included in comparative information: Geoff Lucas Managing Director and Chief Executive Officer (CEO) (ceased 6 August 2024) Information regarding individual Directors and executives’ compensation and some equity instruments disclosures as required by the Corporations Regulations 2M.3.03 is provided in the Remuneration report table on page 17. 2026 2025 $ $ Short-term employee benefits 2,289,430 1,985,941 Post-employment benefits 97,500 99,006 Equity-settled share-based payments – – Other long-term benefits – – Termination benefits – 275,000
Total 2,386,930 2,359,947
Note 18 Related party transactions Some Directors or former Directors of the Group hold or have held positions in other companies, where it is considered that they control or significantly influence the financial or operating policies of those entities. During the year, the following entities provided services to the Group. 18.1 Related party loans Total transactions Receivable/(payable) balance Related party Nature of transactions KMP 2026 2025 2026 2025 $ $ $ $ Matt Lahooda Loans Matt Lahood 355,701 559,291 355,701 559,291
a. As at 30 June 2026, an amount of $355,701 was advanced to Mr Lahood (2025: $559,291). The terms of the advance include: ◼ Principal sum Up to $650,000 ◼ Loan commencement 27 October 2021 ◼ Interest rate 8% per annum (after 12 months from 1 November 2023) ◼ Default interest rate Interest rate above plus 5% per annum ◼ Securities Any future sales commissions and future income and wages as per EA entitlements ◼ Instalment date Due on the final repayment date, or earlier as STI payments and property sales commissions fall due. Discretionary repayments may also be made during the term. ◼ Repayment date 31 December 2026 18.2 Related party financial liabilities As disclosed in note 5.7.3, the Company issued 5,000,000 convertible notes to Peters Investments Pty Ltd (Peters Investments), a related party of the Company. Peters Investments holds 30.48% of the issued ordinary share capital of the Company, and Ms Melissa Peters, managing director of Peters Investments, was appointed a Director of the Company on 1 May 2026 and is accordingly a member of the Group’s key management personnel from that date. The carrying value of the note was $5,532,800 (2025: 4,292,633)
P a g e | 60
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 19 Earnings per share (EPS) Note 2026 2025 $’000 $’000
19.1 Reconciliation of earnings to profit or loss Profit or (loss) for the year (2,372) (5,437) Less: profit attributable to non-controlling equity interest – –
Profit or (loss) used in the calculation of basic and diluted EPS (2,372) (5,437)
2026 2025 No. No.
19.2 Weighted average number of ordinary shares outstanding during the year used in calculation of basic EPS 439,575,921 435,025,231 Weighted average number of dilutive equity instruments outstanding 19.5 N/A N/A
19.3 Weighted average number of ordinary shares outstanding during the year used in calculation of diluted EPS 439,575,921 435,025,231
2026 2025 19.4 Earnings per share ₵ ₵ Basic EPS (cents per share) 19.5 (0.54) (1.25) Diluted EPS (cents per share) 19.5 N/A N/A
19.5 As at 30 June 2026, the Group has 1,500,000 unissued shares under options (2025: 1,500,000) and no performance shares on issue (30 June 2025: nil). The Group’s unissued shares under option and performance shares were anti-dilutive in both 2026 and 2025.
Note 20 Auditor’s remuneration 2026 2025 $ $ Remuneration of the auditor for: ◼ Auditing or reviewing the financial reports: Hall Chadwick WA Audit Pty Ltd 181,000 176,000 ◼ Non-audit services provided by a related practice of the Auditor – –
181,000 176,000
P a g e | 61
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 21 Operating segments 21.1 Identification of reportable segments The Group has identified its operating segments based on the internal reports that are provided to the Board of Directors (the Board) monthly and in determining the allocation of resources. The Group is primarily managed according to its service offerings, as each exhibits distinct risk profiles and performance evaluation criteria. Accordingly, operating segments are determined on this basis. 21.2 Types of services by segment 21.2.1 Real estate property services This represents revenue received from real estate services including selling of property, and settlement agent services. 21.2.2 Property management services This represents revenue received for provision of property management services. 21.2.3 Mortgage origination services In accordance with AASB 8 Operating Segments, the Group has replaced its Mortgage Origination Services segment with Property Management Services following the sale of the mortgage business in the prior financial year. Mortgage origination is no longer material and has been reclassified to other segments in the current period. This change reflects the Group’s current strategic focus. Comparative segment information has been reclassified to ensure consistency with current disclosures and to provide relevant insight into the Group’s performance and resource allocation. 21.2.4 Other This represents non-reportable segments including head office, property investments, and other services. 21.3 Basis of accounting for purposes of reporting by operating segments 21.3.1 Accounting policies adopted Unless otherwise stated, all amounts reported to the Board, being the chief operating decision maker, are prepared in accordance with the accounting policies adopted in the Group’s annual financial statements. 21.3.2 Inter-segment transactions Inter-segment transactions are eliminated on consolidation. Inter-segment loans are initially recognised at the consideration transferred, net of transaction costs. Where such loans are not on commercial terms, they are not adjusted to fair value using market interest rates. This treatment differs from that applied in the statutory financial statements. 21.3.3 Segment assets and liabilities Where an asset is used across multiple segments, the asset is allocated to that segment that receives majority economic value from that asset. Usually, segment assets are clearly identifiable on the basis of their nature and physical location. Liabilities are allocated to segments where there is a direct nexus between the incurrence of the liability and the operations of the segment. Borrowings and tax liabilities are generally considered to relate to the Group as a whole and are not allocated. Segment liabilities include trade and other payables and certain direct borrowings. 21.3.4 Unallocated items The following items of revenue, expenses, assets, and liabilities are not allocated to operating segments as they are not considered part of the core operations of any segment: ◼ Head office and corporate costs; ◼ Net gains on disposal of available-for-sale investments; ◼ Impairment of assets and other non-recurring items of revenue and expense; ◼ Income tax expense, and current and deferred tax assets and liabilities; ◼ Other financial assets; ◼ Intangible assets; and ◼ Discontinued operations. 21.3.5 Segment information a. The Group’s operations are from Australian sources and therefore no geographical segments are disclosed. b. Segmented reporting of assets and liabilities is not provided, as the Board receives information on a consolidated basis.
21.4 Major customers The Group has a diversified range of customers across various geographic locations and businesses, and is not dependent on any one customer above 5%.
P a g e | 62
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 21 Operating segments (cont.)
21.5 Segment financial performance Real estate Property Total property management reportable Other services services segments segments Total 30 June 2026 $’000 $’000 $’000 $’000 $’000 Revenue ◼ External revenues 94,075 14,621 108,696 30 108,726 ◼ Inter-segment revenues – – – – – Total segment revenue – 94,075 14,621 108,696 30 108,726 Total group revenue and other income _ 108,726 Segment EBITDA 13,322 3,185 16,507 – 16,507 ◼ Unallocated corporate costs (11,646) EBITDA _ 4,861 Reconciliation of segment loss to Group loss: (i) Allocated items: ◼ Gain or (loss) on disposal of assets (15) 342 327 12 339 ◼ Depreciation and amortisation (2,057) (1,855) (3,912) (821) (4,733) ◼ Interest received – – – 53 53 ◼ Net finance costs (618) (718) (1,336) (1,103) (2,439) ◼ Legal costs (non-recurring) – – – (107) (107) ◼ Share of profit or (loss) from associate 15 – 15 – 15 (ii) Unallocated items: ◼ Fair value adjustments – – – (361) (361) Loss before income tax _ (2,372) Real estate Property Total property management reportable Other services services segments segments Total 30 June 2025 $’000 $’000 $’000 $’000 $’000 Revenue ◼ External revenues 84,930 13,610 98,540 1 98,541 ◼ Inter-segment revenues – – – – – Total segment revenue 84,930 13,610 98,540 1 98,541 Total group revenue and other income _ 98,541 Segment EBITDA 11,095 3,069 14,164 – 14,164 ◼ Unallocated corporate costs (10,406) EBITDA _ 3,758 Reconciliation of segment loss to Group loss: (i) Allocated items: ◼ Gain or (loss) on disposal of assets 54 13 67 (18) 49 ◼ Depreciation and amortisation (1,749) (4,167) (5,916) (703) (6,619) ◼ Net finance costs (619) (799) (1,418) (1,563) (2,981) ◼ Valuation costs – (30) (30) – (30) ◼ Share of associate profit or (loss) 75 – 75 – 75 (ii) Unallocated items: ◼ Fair value adjustments – – – 311 311 Loss before income tax _ (5,437)
P a g e | 63
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 22 Statement of material accounting policies
This note provides a list of the material accounting policies adopted in the preparation of these consolidated financial statements to the extent they have not already been disclosed in the other notes above. These policies have been consistently applied to all the years presented, unless otherwise stated.
22.1 Basis of preparation 22.1.1 Reporting entity The Agency Group Australia Ltd (The Agency or the Company) is a listed public company limited by shares, domiciled and incorporated in Australia. These are the consolidated financial statements and notes of The Agency and controlled entities (collectively the Group). The financial statements comprise the consolidated financial statements of the Group. For the purposes of preparing the consolidated financial statements, the Company is a for-profit entity. The Group is a for-profit entity and is primarily involved in the integrated real estate services. The separate financial statements of The Agency, as the parent entity, have not been presented with this financial report as permitted by the Corporations Act 2001 (Cth).
22.1.2 Basis of accounting These financial statements are general purpose financial statements which have been prepared in accordance with Australian Accounting Standards and Interpretations of the Australian Accounting Standards Board (AAS Board) and International Financial Reporting Standards (IFRS) as issued by the International Accounting Standards Board (IASB), and the Corporations Act 2001 (Cth). Australian Accounting Standards (AASBs) set out accounting policies that the AAS Board has concluded would result in a financial report containing relevant and reliable information about transactions, events and conditions to which they apply. Compliance with AASBs ensures that the financial statements and notes also comply with IFRS as issued by the IASB. The financial statements were authorised for issue on 31 August 2026 by the Directors of the Company.
22.1.3 Going concern The financial report has been prepared on a going concern basis, which contemplates the continuity of normal business activity and the realisation of assets and the settlement of liabilities in the ordinary course of business. The Group incurred a loss for the year of $2.37 million (2025: $5.44 million loss) and a net cash in-flow from operating activities of $3.52 million (2025: $4.19 million in-flow). The loss for the year was impacted by interest and finance costs ($1.94 million), depreciation and amortisation ($4.73 million), and salaries and employment costs ($88.30 million). These items were partially offset by an increase in revenue to $108.73 million. As at 30 June 2026, the Company had a working capital deficit of $12.97 million (2025: $19.17 million working capital deficit). The Directors have prepared a cash flow forecast, which indicates that the Group will have sufficient cash flows to meet commitments and working capital requirements for the 12-month period from the date of signing this financial report. The ability of the Group to continue as a going concern is principally dependent on the following: ◼ The Group continuing to generate cash flows from operations; and ◼ The Group not breaching the terms of its borrowing facilities. As disclosed in note 5.6.3, the Group continues to have access to its financing facility with Macquarie Bank Limited. The total facility is $10.0 million, of which $8.4 million had been drawn as at 30 June 2026, leaving $1.6 million available for further drawdown. Peters Investments has also reaffirmed its ongoing support through the renewal of its facility. Should the Group require additional working capital or be required to refinance or repay its existing facilities, the Directors are confident that alternative financing arrangements could be secured and/or further asset sales undertaken. The Group continues to hold significant value in its rent roll assets that is not recognised on the balance sheet. The Group’s most recent independent professional valuation of its rent rolls indicates a market value of approximately $38.10 million (2025: $37.41 million), representing approximately $35.42 million (2025: $34.40 million) of value in excess of the carrying amount recognised on the balance sheet. Based on the Group’s cash flow forecasts, available financing facilities and the other factors referred to above, the Directors are satisfied that the going concern basis of preparation remains appropriate. In particular, having regard to the Group’s access to existing funding, the value of its underlying assets and its demonstrated ability to raise capital, the Directors are confident in the Group’s ability to meet its obligations and obtain additional funding as and when required.
P a g e | 64
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 22 Statement of material accounting policies
22.1.4 Comparative figures Where required by AASBs comparative figures have been adjusted to conform to changes in presentation for the current financial year. Where the Group retrospectively applies an accounting policy, makes a retrospective restatement or reclassifies items in its financial statements, an additional (third) statement of financial position as at the beginning of the preceding period in addition to the minimum comparative financial statements is presented. 22.1.5 New and amended AASBs adopted by the Group A number of amended AASBs became applicable for the current reporting period. The group did not have to change its accounting policies or make retrospective adjustments as a result of adopting these AASBs. 22.2 Goods and Services Tax Goods and Services Tax (GST) is an Australian broad-based consumption tax that the Group is exposed to. Revenues, expenses, and assets are recognised net of the amount of GST, except where the amount of GST incurred is not recoverable from the taxation authority. In these circumstances the GST is recognised as part of the cost of acquisition of the asset or as part of an item of the expense. Receivables and payables in the statement of financial position are shown inclusive of GST. The net amount of GST recoverable from, or payable to, the Australian Taxation Office (or jurisdictional equivalent) is included as a current asset or liability in the balance sheet. Cash flows are presented in the statement of cash flows on a gross basis, except for the GST component of investing and financing activities, which are disclosed as operating cash flows. Commitments and contingencies are disclosed net of the GST recoverable from, or payable to, the taxation authority. 22.3 Foreign currency transactions and balances 22.3.1 Functional and presentation currency The functional currency of each of the Group’s entities is measured using the currency of the primary economic environment in which that entity operates. The consolidated financial statements are presented in Australian dollars which is the legal parent entity’s functional and presentation currency. The functional currency of the Group is the Australian Dollar. 22.4 Use of estimates and judgements The preparation of consolidated financial statements requires management to make judgements, estimates and assumptions that affect the application of policies and reported amounts of assets and liabilities, income and expenses. These estimates and associated assumptions are based on historical experience and various factors that are believed to be reasonable under the circumstances, the results of which form the basis of making the judgements about carrying values of assets and liabilities that are not readily apparent from other sources. Actual results may differ from these estimates. Estimates and underlying assumptions are reviewed on an ongoing basis. Revisions to accounting estimates are recognised in the period in which the estimate is revised and in any future periods affected. Judgements made by management in the application of AASBs that have significant effect on the consolidated financial statements and estimates with a significant risk of material adjustment in the next year are discussed in note 22.4.1. 22.4.1 Critical accounting estimates and judgements Management discusses with the Board the development, selection and disclosure of the Group’s critical accounting policies and estimates and the application of these policies and estimates. The estimates and judgements that have a significant risk of causing a material adjustment to the carrying amounts of assets and liabilities within the next financial year are discussed below. a. Key estimate – Taxation ……………………………………………………………………………. Refer note 4.8 Income tax. b. Key judgement and key estimate – Impairment of goodwill and rent rolls……… Refer note 6.3 Intangible assets. c. Key judgement – determining the lease term ……………………………………………… Refer note 6.2 Leases. d. Key estimate – determining convertible note embedded derivative ……………… Refer note 5.7 Financial liabilities.
22.5 Fair value 22.5.1 Fair value of assets and liabilities The Group measures some of its assets and liabilities at fair value on either a recurring or non-recurring basis, depending on the requirements of the applicable AASB. Fair value is the price the Group would receive to sell an asset or would have to pay to transfer a liability in an orderly unforced transaction between independent, knowledgeable, and willing market participants at the measurement date.
P a g e | 65
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Notes to the consolidated financial statements for the year ended 30 June 2026
Note 22 Statement of material accounting policies As fair value is a market-based measure, the closest equivalent observable market pricing information is used to determine fair value. Adjustments to market values may be made having regard to the characteristics of the specific asset or liability. The fair values of assets and liabilities that are not traded in an active market are determined using one or more valuation techniques. These valuation techniques maximise, to the extent possible, the use of observable market data. Where possible, market information is obtained from the principal market for the asset or liability, being the market with the highest volume and level of activity. In the absence of a principal market, the most advantageous market available at the reporting date is used. This is the market that maximises the proceeds from the sale of the asset or minimises the payments to transfer the liability, after considering transaction and transport costs. For non-financial assets, the fair value measurement also considers a market participant’s ability to use the asset in its highest and best use or to sell it to another market participant that would use the asset in its highest and best use. The fair value of liabilities and the entity’s own equity instruments (excluding share-based payment arrangements) may be measured, in the absence of an observable market price, by reference to market information where such instruments are held as assets. Where this is not available, other valuation techniques are applied and, where material, disclosed in the relevant note to the financial statements. 22.5.2 Fair value hierarchy AASB 13 Fair Value Measurement requires the disclosure of fair value information by level of the fair value hierarchy, which categorises fair value measurements into one of three possible levels based on the lowest level that an input that is significant to the measurement can be categorised into as follows: Level 1 Level 2 Level 3 Measurements based on quoted prices Measurements based on inputs other than Measurements based on unobservable (unadjusted) in active markets for identical quoted prices included in Level 1 that are inputs for the asset or liability. assets or liabilities that the entity can observable for the asset or liability, either access at the measurement date. directly or indirectly.
The fair values of assets and liabilities that are not traded in an active market are determined using one or more valuation techniques. These valuation techniques maximise, to the extent possible, the use of observable market data. If all significant inputs required to measure fair value are observable, the asset or liability is included in Level 2. If one or more significant inputs are not based on observable market data, the asset or liability is included in Level 3. The Group would change the categorisation within the fair value hierarchy only in the following circumstances: ◼ if a market that was previously considered active (Level 1) became inactive (Level 2 or Level 3) or vice versa; or ◼ if significant inputs that were previously unobservable (Level 3) became observable (Level 2) or vice versa. When a change in the categorisation occurs, the Group recognises transfers between levels of the fair value hierarchy (i.e., transfers into and out of each level of the fair value hierarchy) on the date the event or change in circumstances occurred. 22.5.3 Valuation techniques The Group selects a valuation technique that is appropriate in the circumstances and for which sufficient data is available to measure fair value. The availability of sufficient and relevant data primarily depends on the specific characteristics of the asset or liability being measured. The valuation techniques selected by the Group are consistent with one or more of the following valuation approaches: ◼ Market approach: valuation techniques that use prices and other relevant information generated by market transactions for identical or similar assets or liabilities. ◼ Income approach: valuation techniques that convert estimated future cash flows or income and expenses into a single discounted present value. ◼ Cost approach: valuation techniques that reflect the current replacement cost of an asset at its current service capacity. Each valuation technique requires inputs reflecting the assumptions buyers and sellers would use when pricing the asset or liability, including risks. The Group prioritises techniques that maximise observable inputs and minimise unobservable inputs. Observable inputs are those based on market data, such as publicly available transaction information, that reflect assumptions generally used by market participants. Unobservable inputs are those for which market data is unavailable and are developed using the best information available. 22.6 New Accounting Standards and Interpretations not yet mandatory or early adopted Certain new accounting standards and interpretations have been published that are not mandatory for 30 June 2026 reporting periods and have not been early adopted by the Group. These standards are not expected to have a material impact on the entity in the current or future reporting periods and on foreseeable future transactions.
P a g e | 66
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Consolidated Entity Disclosure Statement Entity name Ownership Type of entity Trustee, Country of Australian Foreign interest partner, or incorporation resident for jurisdiction(s) 2026 participant in tax purposes of foreign a joint venture residents ◼ The Agency Group Australia Ltd Parent Body corporate N/A Australia Australian N/A ◼ Agency Partners WA Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ Ausnet Financial Planning Services Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ Ausnet Financial Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ Ausnet Property Investment Fund Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ Ausnet Real Estate Services Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ Courtesy Real Estate (NSW) Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ Jelina Holdings Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ Move Property Solutions Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ S.J. Laing & Son Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency Auctions NSW Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency Canberra Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency Marketing Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency MDC QLD Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency MDC Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency Project Sales NSW Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency Project Sales QLD Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency Project Sales VIC Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency Property Management NSW Pty 100 Body corporate N/A Australia Australian N/A Ltd ◼ The Agency Real Estate Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency Sales NSW Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency Sales QLD Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency Sales VIC Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency Strata Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Agency Tasmania Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ The Real Estate Group Australia Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ Top Level Real Estate Holdings Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ Top Level Real Estate Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ Top Level Real Estate Sales Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ Value Partner Program Pty Ltd 100 Body corporate N/A Australia Australian N/A ◼ Vision Capital Management Ltd 100 Body corporate N/A Australia Australian N/A ◼ Westvalley Corporation Pty Ltd 20 Body corporate N/A Australia Australian N/A
The Agency Group Australia Ltd and its wholly-owned Australian subsidiaries have formed an income tax consolidated group (the Tax Group) under the tax consolidation legislation. Each entity in the Tax Group recognises its own current and deferred tax liabilities (DTL), except for any DTLs resulting from unused tax losses and tax credits, which are immediately assumed by the parent entity. The Group notified the Australian Tax Office that it had formed a Tax Group to apply from 1 July 2019. The Tax Group has entered a tax sharing agreement whereby each company in the Tax Group contributes to the income tax payable in proportion to their contribution to the net profit before tax of the Tax Group.
P a g e | 67
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Consolidated Entity Disclosure Statement (cont.)
Basis of preparation
This Consolidated Entity Disclosure Statement (CEDS) has been prepared in accordance with the Corporations Act 2001 (Cth). It includes certain information for each entity that was part of the consolidated entity at the end of the financial year.
Determination of Tax Residency Section 295(3A) of the Corporations Act 2001 (Cth) defines tax residency as having the meaning in the Income Tax Assessment Act 1997. The determination of tax residency involves judgement as there are currently several different interpretations that could be adopted, and which could give rise to a different conclusion on residency. It should be noted that the definitions of “Australian resident” and “foreign resident” in the Income Tax Assessment Act 1997 are mutually exclusive. This means that if an entity is an Australian resident, it cannot be a foreign resident for the purposes of disclosure in the CEDS. In determining tax residency, the consolidated entity has applied the following interpretation:
Australian tax residency The consolidated entity has applied current legislation and judicial precedent, including having regard to the Tax Commissioner’s public guidance in Tax Ruling TR 2018/5.
P a g e | 68
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Directors’ declaration
The Directors of the Company declare that in the Directors’ opinion: 1. The attached financial statements and notes, as set out on pages 21 to 66, are in accordance with the Corporations Act 2001 (Cth) including: (a) complying with Accounting Standards, the Corporations Regulations 2001, and other mandatory professional reporting requirements; and (b) giving a true and fair view of the consolidated entity’s financial position as at 30 June 2026 and of its performance for the financial year ended on that date 2. there are reasonable grounds to believe that the Company will be able to pay its debts as and when they become due and payable.
Note 22.1.2 confirms that the financial statements also comply with International Financial Reporting Standards as issued by the International Accounting Standards Board.
The Directors have been given the declarations by the chief executive officer and chief financial officer required by section 295A of the Corporations Act 2001 (Cth).
The Consolidated Entity Disclosure Statement on page 67 is true and correct as at 30 June 2026.
This declaration is signed in accordance with a resolution of the Directors made pursuant to section 295(5) of the Corporations Act 2001 (Cth).
On behalf of the Directors
ANDREW JENSEN Executive Chairman Dated this Monday, 31 August 2026
P a g e | 69
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Independent auditor’s report
P a g e | 70
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
P a g e | 71
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
P a g e | 72
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
P a g e | 73
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
P a g e | 74
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
P a g e | 75
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Corporate governance statement The Board is responsible for establishing the Company’s corporate governance framework. In establishing its corporate governance framework, the Board has referred to the 4th edition of the ASX Corporate Governance Council’s Corporate Governance Principles and Recommendations.
The Corporate Governance Statement discloses the extent to which the Company follows the recommendations. The Company will follow each recommendation where the Board has considered the recommendation to be an appropriate benchmark for its corporate governance practices. Where the Company’s corporate governance practices will follow a recommendation, the Board has made appropriate statements reporting on the adoption of the recommendation. In compliance with the “if not, why not” reporting regime, where, after due consideration, the Company’s corporate governance practices will not follow a recommendation, the Board has explained its reasons for not following the recommendation and disclosed what, if any, alternative practices the Company will adopt instead of those in the recommendation.
The Company’s governance-related documents can be found on its website at www.investors.theagency.com.au/corporate- governance.
P a g e | 76
THE AGENCY GROUP AUSTRALIA LTD ANNUAL REPORT AND CONTROLLED ENTITIES 30 June 2026 ABN 52 118 913 232
Additional Information for Listed Public Companies The following additional information is required by the Australian Securities Exchange in respect of listed public companies. 1 Capital as at 6 August 2026
a. Ordinary share capital 439,576,589 ordinary fully paid shares held by 815 shareholders.
b. Options over Unissued Shares Number of Exercise Price Expiry ASX Options $ Date Status 1,500,000 0.050 30 November 2026 Unlisted
1,500,000
c. Voting rights The voting rights attached to each class of equity security are as follows: ◼ Ordinary shares: Each ordinary share is entitled to one vote when a poll is called, otherwise each member present at a meeting or by proxy has one vote on a show of hands. ◼ Options: Options do not entitle the holders to vote in respect of that equity instrument, nor participate in dividends, when declared, until such time as the options are exercised or performance shares convert and subsequently registered as ordinary shares.
d. Substantial Shareholders as at 6 August 2026 Name Number of Ordinary % Held of Issued Ordinary Fully Paid Shares Held Capital Peters Investments Pty Ltd 134,000,000 30.48 Ben Collier Investments Pty Ltd <Ben Collier Investments P/L> 27,060,515 6.16 MAK Property Group Pty Ltd <MAK A/C> 25,690,547 5.84 Teldar Real Estate Pty Ltd <MJ Lahood Family A/C> 24,349,790 5.54
e. Distribution of Shareholders as at 6 August 2026 Category (size of holding) Total Holders Number % Held of Issued Ordinary Ordinary Capital 1 – 1,000 204 33,298 0.01 1,001 – 5,000 96 265,400 0.06 5,001 – 10,000 86 664,282 0.15 10,001 – 100,000 272 10,183,904 2.32 100,001 – and over 157 428,429,705 97.46
815 439,576,589 100.00
f. Unmarketable Parcels as at 6 August 2026 Based on the price per security, number of holders with an unmarketable holding: 439, with total 1,621,971, amounting to 0.37% of issued capital.
g. On-Market Buy-Back There is no current on-market buy-back.
h. Restricted Securities The Company currently has no restricted securities. However, ordinary shares issued upon conversion of the Performance Rights will be voluntarily escrowed for one year from the date of issue of the Shares.
P a g e | 77
ANNUAL REPORT THE AGENCY GROUP AUSTRALIA LTD 30 June 2026 AND CONTROLLED ENTITIES ABN 52 118 913 232
Additional Information for Listed Public Companies
i. 20 Largest Shareholders — Ordinary Shares as at 6 August 2026 Rank Name Number of Ordinary % Held of Issued Fully Paid Shares Held Ordinary Capital 1. Peters Investments Pty Ltd 134,000,000 30.48 2. Ben Collier Investments Pty Ltd <Ben Collier Investments P/L> 27,060,515 6.16 3. MAK Property Group Pty Ltd <MAK A/C> 25,690,547 5.84 4. Teldar Real Estate Pty Ltd <MJ Lahood Family A/C> 24,349,790 5.54 5. 1800Homeloans Pty Ltd <Phoenix Aggregation A/C> 19,624,130 4.46 6. SEMC 2 Pty Limited <The Chen Asset A/C> 17,475,530 3.98 7. Hanzheng KSW Pty Ltd <Hanzheng KSW Unit A/C> 16,666,667 3.79 8. Trindis Pty Ltd 14,186,951 3.23 9. Mr Irwin David Klotz 10,500,000 2.39 10. SMATS Consortium Pty Ltd 8,401,713 1.91 11. Dawney & Co Ltd 8,000,000 1.82 12. Trilogy Services Pty Ltd <Trilogy Services A/C> 7,692,308 1.75 13. Coast Equity Pty Ltd <The Fogarty Super Fund A/C> 7,000,000 1.59 14. Mr James John Clive Rodda 6,728,592 1.53 15. Mr Clinton James Quay 5,054,909 1.15 16. Martianne Pty Ltd <Crabb Family Invest No 2 A/C> 5,000,000 1.14 17. Profess Investments Pty Ltd <Brutus Superannuation A/C> 4,886,026 1.11 18. BNP Paribas 4,690,183 1.07 19. Mr Subodh Raja Kode 2,882,766 0.66 20. Mr Christopher Charles Alexander Lowry 2,713,711 0.62
Total 352,604,338 80.22
j. Unquoted Securities Holders Holding More than 20% of the Class as at 6 August 2026
◼ Unlisted Options (Exercise price $0.05, Expiry Date: 30.11.26) Rank Name Number of Unquoted % Held of Unquoted Securities Security Class 1. Hawera Pty Ltd <The Bailey Family A/C> 600,000 40.00 2. Mr Peter Darren Russell 600,000 40.00 3. Sabre Power Systems Pty Ltd 300,000 20.00
Total 1,500,000 100.00
Total Unlisted Options (Exercise price $0.05, Expiry Date: 30.11.26) 1,500,000
2 The Company Secretary is Stuart Usher.
3 Principal registered office As disclosed in note Company details on page 25 of this Annual Report.
4 Registers of securities As disclosed in the Corporate directory on page i of this Annual Report.
5 Stock exchange listing Quotation has been granted for all the ordinary shares of the Company on all Member Exchanges of the Australian Securities Exchange Limited, as disclosed in the Corporate directory on page i of this Annual Report.
P a g e | 78